CheckEmoji Community · the emoji forum
🏠 Home 🆕 What's new ❓ Unanswered 🔥 Popular 📡 RSS Members 👥 0 online log in · register
Home › Society › Economy › Banking, Insurance & Loans › AARP (and related discussions on Swiss Franc loans) (II)

AARP (and related discussions on Swiss Franc loans) (II)

Started by Andrew Booth29 · · 👁 15 views · 351 replies

📡 Subscribe to replies

Participants Andrew Booth29Robin Bailey7Timothy Kim9Jesse Flores842mellowotter17Thomas Clark91rowdyraven112mistydrifter56Peter Palmernimblelynx63Linda Anderson7Patrick Carter5Nathan Reyes56Rebecca Green7coastalpanther89Gregory Wells5Michael Baker75Noah Perez5Jeremy Carter2Daniel Doyle11Megan Roberts7Tyler Richardson4Douglas Reed4granitecyclist …
briskcanyon12 briskcanyon12 Member
44 messages
joined Nov 2022
#281 ·
I am honestly fascinated by how creative you all are when it comes to twisting facts and digging up excuses. Your grasp of legal technicalities is truly enviable. It begs a very logical question: if you are all such brilliant legal minds, why on earth did you take out a Swiss Franc Loan in the first place? Why would anyone sign such disastrous loan agreements if they were as smart as you claim to be now?

I’m curious—how would you react if you lent some Swiss Francs to a friend, and when it came time for them to pay you back, they showed up with this exact same nonsense you're peddling right now?

At the European Union level, a political decision was made to provide assistance to those who took out Swiss Franc loans. Laws and directives were adjusted specifically to make this legally possible. Depending on the level of populism in a given country, the implementation varied—some places leaned more toward the consumer than others. Instead of accepting this as a form of aid, you choose to spin tales, trying to convince everyone else that you are victims fighting solely for your rights, while ignoring the fact that you're essentially asking for handouts at the expense of all the other "idiots" who were smart enough not to touch these loans.

Your ultimate goal is simply to get your apartment for free, and maybe even squeeze out a little extra pocket money on top of that. Only then will "justice," according to your logic, finally be served.

The interest rate hikes fall into a gray area because the parameters weren't strictly defined, which was a massive mistake. However, rates climbed because of the crisis; the government had to borrow more expensively due to rising risk. It wasn't like the banks decided to hike rates just for the hell of it. The US had to take on debt in dollars at 6-7% because, within the context of the European Union, finding buyers for bonds was difficult when the EUR/USD exchange rate was sitting above 1.2 or perhaps 1.3. Now, they are paying interest and returning principal at an exchange rate of 1 or 1.05. Honestly, they should have asked you for advice on how to explain to Americans why they need to convert those bonds from EUR! We are part of the European Union, after all.
hollowangler11 hollowangler11 Newcomer
2 messages
joined Feb 2021
#282 ·
Man, I’m just sitting here thinking about how that thing crawled right back out from under the rock again...
Zachary Wood77 Zachary Wood77 Newcomer
5 messages
joined Apr 2019
#283 ·
hollowangler11 said:Man, I’m just sitting here thinking about how that thing crawled right back out from under the rock again...

Is this just more aggressive marketing from the new CEO? 😁
Walter Thomas18 Walter Thomas18 Active Member
83 messages
joined Nov 2022
#284 ·
frozencanyon14 said:You’re honestly acting like you don't get it—we borrowed CHF (nobody is arguing that part), the value of the CHF shot through the roof, and during that SAME PERIOD, the bank kept hiking interest rates (in my case, FOUR different times!!!). And you're telling me that was fine and legal? Well, in our corrupt system, they actually say it isn't. The proof is in the sheer number of people who sued their banks and actually won.

I'LL SAY IT AGAIN: if you haven't sued your bank yet and you were stuck with a non-convertible loan, you better do it, because you're almost certainly going to win.

If you actually read my posts, you’d see I’m only saying that the interest rates were the one bad thing banks did, and that they should be punished for it. That is my only point.
When it comes to the principal, it has absolutely nothing to do with interest rates. If you borrow 100 of something, you owe 100 of that thing—plus interest. Principal is one thing; total debt is something else entirely. If you borrow 100 today and pay it back the same day, you’re paying back exactly 100. Once a single day passes, interest enters the equation.
Zachary Wood77 Zachary Wood77 Newcomer
5 messages
joined Apr 2019
#285 ·
Walter Thomas18 said:If you actually read my posts, you’d see I’m only saying that the interest rates were the one bad thing banks did, and that they should be punished for it. That is my only point.
When it comes to the principal, it has absolutely nothing to do with interest rates. If you borrow 100 of something, you owe 100 of that thing—plus interest. Principal is one thing; total debt is something else entirely. If you borrow 100 today and pay it back the same day, you’re paying back exactly 100. Once a single day passes, interest enters the equation.

It really isn't as simple as you're trying to make it. Look, if you borrowed Euros, you received the equivalent value in Dollars; over ten years, you might have ended up with more or less the same amount of Dollars for those Euros simply because the Federal Reserve kept the exchange rate stable. With the Swiss Franc, that wasn't the case. The Federal Reserve should have stepped in the moment those Swiss Franc Loans started appearing, because they were essentially speculative products from the get-go. We all know how that story ended—there's a reason the US Supreme Court eventually declared those Swiss Franc clauses null and void.
Casey Cook10 Casey Cook10 Active Member
77 messages
joined May 2024
#286 ·
Richard Taylor3 said:You signed the contract agreeing to the terms. Why should American taxpayers be stuck footing the bill for your bad investment calls?

I mean, I'm just wondering how the average taxpayer even gets pulled into a legal battle between a client and a bank in the first place, maybe?
Casey Cook10 Casey Cook10 Active Member
77 messages
joined May 2024
#287 ·
Walter Thomas18 said:Exactly. If the Swiss Franc had "tanked," they would be mocking those who opted for USD or Euro loans instead.

So, after ten years of this nonsense, I guess we’re still stuck listening to the same old nonsense from folks like this.
I mean, if someone is saying this in 2023, they either have no clue what happened or they're basically just a mouthpiece for the big banks.
Let me say this one more time, and really, just this once: the banks protected themselves by using those variable interest rates that they kept hiking without any real logic behind it.
It’s kind of funny, though... when the exchange rate went up, the interest rates didn't drop. They stayed right where they were... or wait, I guess they actually went up? Pretty wild.
Walter Thomas18 Walter Thomas18 Active Member
83 messages
joined Nov 2022
#288 ·
Zachary Wood77 said:It really isn't as simple as you're trying to make it. Look, if you borrowed Euros, you received the equivalent value in Dollars; over ten years, you might have ended up with more or less the same amount of Dollars for those Euros simply because the Federal Reserve kept the exchange rate stable. With the Swiss Franc, that wasn't the case. The Federal Reserve should have stepped in the moment those Swiss Franc Loans started appearing, because they were essentially speculative products from the get-go. We all know how that story ended—there's a reason the US Supreme Court eventually declared those Swiss Franc clauses null and void.

The Federal Reserve did react—they warned people against taking out loans with a Swiss Franc currency clause.

Of course you received the equivalent in Dollars; back then, the Dollar was the legal tender in America. That doesn't mean you weren't allowed to buy foreign currency; it just means you couldn't legally use those foreign funds to pay bills in the US. That is why the Swiss Franc was converted to Dollars at the rate on the day of disbursement. Consequently, you pay your annuities in Swiss Francs based on the rate on the day of payment. If the Swiss Franc had dropped, you would have paid fewer Dollars. But it didn't drop; it rose, and our banks had absolutely no influence over that. Anyone who thinks they did is giving our banks far too much importance.
When you take out a loan with a currency clause, you are essentially "betting" on the exchange rate (hoping it stays stable or that the foreign currency loses value). You lost the bet, and now you're blaming everyone else.
If the Swiss Franc rate had fallen, you would have been celebrating. One of the loudest voices in the "Swissman" case was trumpeting about how he screwed the banks because he took out a Swiss Franc loan and used it to close his debt in Dollars or Euros—I can't remember which. He thought he was brilliant, but he turned out to be quite foolish. Later, he claimed he didn't understand what a currency clause meant. Please...
Walter Thomas18 Walter Thomas18 Active Member
83 messages
joined Nov 2022
#289 ·
Casey Cook10 said:So, after ten years of this nonsense, I guess we’re still stuck listening to the same old nonsense from folks like this.
I mean, if someone is saying this in 2023, they either have no clue what happened or they're basically just a mouthpiece for the big banks.
Let me say this one more time, and really, just this once: the banks protected themselves by using those variable interest rates that they kept hiking without any real logic behind it.
It’s kind of funny, though... when the exchange rate went up, the interest rates didn't drop. They stayed right where they were... or wait, I guess they actually went up? Pretty wild.

Interest rates rose because all rates were rising, including savings rates.
Regarding the variable interest rate where changes were made per Bank Board Decision—that was indeed a disaster. But look, if the Swiss Franc had plummeted by 30%, the interest rate would have had to rise above the legal maximum just to keep the debt amount constant. In that scenario, you wouldn't even be able to stay at the same level of debt in USD. Instead, the Swiss Franc shot through the roof, soaring over 40%. If it had crashed that hard, there isn't a legally permissible interest rate in existence that could have offset the loss.
Casey Cook10 Casey Cook10 Active Member
77 messages
joined May 2024
#290 ·
Walter Thomas18 said:Interest rates rose because all rates were rising, including savings rates.
Regarding the variable interest rate where changes were made per Bank Board Decision—that was indeed a disaster. But look, if the Swiss Franc had plummeted by 30%, the interest rate would have had to rise above the legal maximum just to keep the debt amount constant. In that scenario, you wouldn't even be able to stay at the same level of debt in USD. Instead, the Swiss Franc shot through the roof, soaring over 40%. If it had crashed that hard, there isn't a legally permissible interest rate in existence that could have offset the loss.

But I guess, whose fault is that? Mine?
The bank really should have figured out how to manage their own supply of those Swiss Francs they were buying with my dollars every single month just to balance their books.

Walter Thomas18 said:Interest rates rose because all rates were rising, including savings rates.
Regarding the variable interest rate where changes were made per Bank Board Decision—that was indeed a disaster. But look, if the Swiss Franc had plummeted by 30%, the interest rate would have had to rise above the legal maximum just to keep the debt amount constant. In that scenario, you wouldn't even be able to stay at the same level of debt in USD. Instead, the Swiss Franc shot through the roof, soaring over 40%. If it had crashed that hard, there isn't a legally permissible interest rate in existence that could have offset the loss.

Wait, which Bank Board Decision are we talking about when it comes to the maximum possible rate???
Back when the Swiss Franc was surging and they were buying it up, LIBOR was basically zero. So, I mean, they just bumped up the portion of the rate that doesn't involve interbank lending...
It's all been laid out already, both in the news and in the US Judiciary...

Don't even try to troll me...
Casey Cook10 Casey Cook10 Active Member
77 messages
joined May 2024
#291 ·
Walter Thomas18 said:The Federal Reserve did react—they warned people against taking out loans with a Swiss Franc currency clause.

Of course you received the equivalent in Dollars; back then, the Dollar was the legal tender in America. That doesn't mean you weren't allowed to buy foreign currency; it just means you couldn't legally use those foreign funds to pay bills in the US. That is why the Swiss Franc was converted to Dollars at the rate on the day of disbursement. Consequently, you pay your annuities in Swiss Francs based on the rate on the day of payment. If the Swiss Franc had dropped, you would have paid fewer Dollars. But it didn't drop; it rose, and our banks had absolutely no influence over that. Anyone who thinks they did is giving our banks far too much importance.
When you take out a loan with a currency clause, you are essentially "betting" on the exchange rate (hoping it stays stable or that the foreign currency loses value). You lost the bet, and now you're blaming everyone else.
If the Swiss Franc rate had fallen, you would have been celebrating. One of the loudest voices in the "Swissman" case was trumpeting about how he screwed the banks because he took out a Swiss Franc loan and used it to close his debt in Dollars or Euros—I can't remember which. He thought he was brilliant, but he turned out to be quite foolish. Later, he claimed he didn't understand what a currency clause meant. Please...

So, they just dropped a single little line in their own newsletter? Wow, what a massive warning right there.
I mean, I guess you have to wonder if they ever actually told their tellers above a certain level to steer clear of those loans. Most of the folks working at the counters probably didn't give a damn...
And the branch managers? Not a chance.

Plus, with how they handled collateral requirements—like not requiring guarantors, for instance—it feels like they were subtly nudging everyone right toward those exact loans.
frozencanyon14 frozencanyon14 Member
12 messages
joined Feb 2021
#292 ·
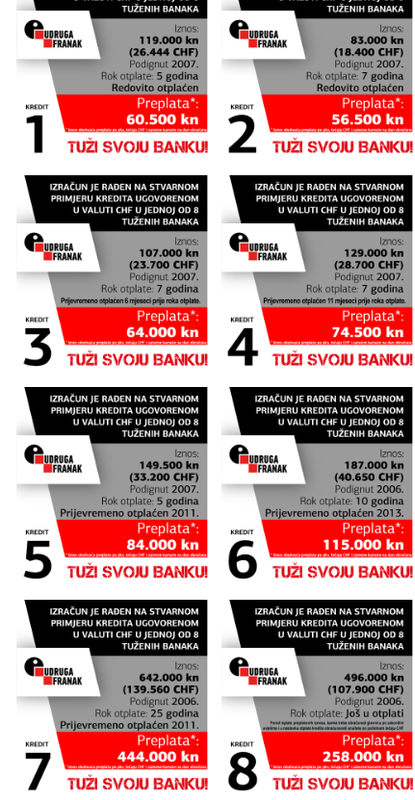
So, I just got an email from AARP—well, the group handling those Swiss Franc Loan issues—and basically, they’re thanking everyone who showed up at the protest and encouraging people to take their banks to court. They said something like this:

In our effort to make the process of getting to court and securing your compensation a little easier, we've set up a dedicated page on our website


We’ve put together a sort of guide there containing everything you might need to know about filing a lawsuit. They even listed some examples of subscription fees below:

image
Walter Thomas18 Walter Thomas18 Active Member
83 messages
joined Nov 2022
#293 ·
Casey Cook10 said:But I guess, whose fault is that? Mine?
The bank really should have figured out how to manage their own supply of those Swiss Francs they were buying with my dollars every single month just to balance their books.

Wait, which Bank Board Decision are we talking about when it comes to the maximum possible rate???
Back when the Swiss Franc was surging and they were buying it up, LIBOR was basically zero. So, I mean, they just bumped up the portion of the rate that doesn't involve interbank lending...
It's all been laid out already, both in the news and in the US Judiciary...

Don't even try to troll me...

You lack any sense of logic, yet you accuse me of trolling!?
Is your problem that the interest rate went up? Yes. You signed a variable rate agreement, so it became your problem. If the rate had been fixed, then it would have been the bank's problem.

If bank boards were allowed to decide whatever maximum interest rate they wanted, they would be significantly larger than they currently are. However, the highest interest rates aren't set by bank boards; they are set by the regulators.
Walter Thomas18 Walter Thomas18 Active Member
83 messages
joined Nov 2022
#294 ·
Casey Cook10 said:So, they just dropped a single little line in their own newsletter? Wow, what a massive warning right there.
I mean, I guess you have to wonder if they ever actually told their tellers above a certain level to steer clear of those loans. Most of the folks working at the counters probably didn't give a damn...
And the branch managers? Not a chance.

Plus, with how they handled collateral requirements—like not requiring guarantors, for instance—it feels like they were subtly nudging everyone right toward those exact loans.

If you crawled into a cave, then sure, you couldn't hear the warnings. But if you watched TV, read the news, or checked online portals, you absolutely could have been aware. All that does is prove you didn't care about any warnings; you just wanted to sign the contract and get that money into your account as fast as possible.

Even the bank employees themselves were taking out Swiss Franc Loans because they were either careless or simply didn't care what they were signing.
Casey Cook10 Casey Cook10 Active Member
77 messages
joined May 2024
#295 ·
Walter Thomas18 said:If you crawled into a cave, then sure, you couldn't hear the warnings. But if you watched TV, read the news, or checked online portals, you absolutely could have been aware. All that does is prove you didn't care about any warnings; you just wanted to sign the contract and get that money into your account as fast as possible.

Even the bank employees themselves were taking out Swiss Franc Loans because they were either careless or simply didn't care what they were signing.

Well, obviously... it was all over the massive billboards.
And Iván Rohatinski mentioned right there in the US Congress where those warnings were supposed to be. I already told you exactly where...

It was basically just the low-level bank staff signing those contracts.
The higher-ups were getting tips.
So, how on earth were the people who were being tipped off supposed to know?

Come on, don't embarrass yourself...
The whole product was broken and compromised from the start, specifically targeted and marketed... Consumers fought back and won their rights in court (including within the European Union).
The fact that certain members of the Democratic Party are shaking things up here at the US Supreme Court is honestly just an embarrassment to the US Judiciary.

I guess you can tell how much influence he should actually have by looking at this...

https://groups.google.com/g/cro-news...sMuR6LQJ?pli=1
Richard Taylor3 Richard Taylor3 Member
12 messages
joined Apr 2023
#296 ·
Casey Cook10 said:I mean, I'm just wondering how the average taxpayer even gets pulled into a legal battle between a client and a bank in the first place, maybe?

Well, look, the Banks actually took the government to international arbitration courts. And since those courts would have almost certainly ruled in favor of the banks, the government ended up settling with them behind closed doors—it was all kept strictly confidential. I mean, why else would they keep it secret? And if you ask me, who do you think covered the losses caused by the government's conversion law? It wasn't just magic; someone had to pay the bill.
Richard Taylor3 Richard Taylor3 Member
12 messages
joined Apr 2023
#297 ·
Walter Thomas18 said:The Federal Reserve did react—they warned people against taking out loans with a Swiss Franc currency clause.

Of course you received the equivalent in Dollars; back then, the Dollar was the legal tender in America. That doesn't mean you weren't allowed to buy foreign currency; it just means you couldn't legally use those foreign funds to pay bills in the US. That is why the Swiss Franc was converted to Dollars at the rate on the day of disbursement. Consequently, you pay your annuities in Swiss Francs based on the rate on the day of payment. If the Swiss Franc had dropped, you would have paid fewer Dollars. But it didn't drop; it rose, and our banks had absolutely no influence over that. Anyone who thinks they did is giving our banks far too much importance.
When you take out a loan with a currency clause, you are essentially "betting" on the exchange rate (hoping it stays stable or that the foreign currency loses value). You lost the bet, and now you're blaming everyone else.
If the Swiss Franc rate had fallen, you would have been celebrating. One of the loudest voices in the "Swissman" case was trumpeting about how he screwed the banks because he took out a Swiss Franc loan and used it to close his debt in Dollars or Euros—I can't remember which. He thought he was brilliant, but he turned out to be quite foolish. Later, he claimed he didn't understand what a currency clause meant. Please...

I’m pretty sure that was Aleksic. He actually ended up becoming one of the main leaders of that massive crusade that eventually led to that law where every single taxpayer in the USA had to foot the bill to compensate the banks during the conversion process. It was a pretty slick move on their part—they worked right alongside the Democratic Party to pull it all off perfectly.
Richard Taylor3 Richard Taylor3 Member
12 messages
joined Apr 2023
#298 ·
Casey Cook10 said:So, they just dropped a single little line in their own newsletter? Wow, what a massive warning right there.
I mean, I guess you have to wonder if they ever actually told their tellers above a certain level to steer clear of those loans. Most of the folks working at the counters probably didn't give a damn...
And the branch managers? Not a chance.

Plus, with how they handled collateral requirements—like not requiring guarantors, for instance—it feels like they were subtly nudging everyone right toward those exact loans.

That’s just not true—Vujcic actually warned people about the dangers of the Swiss Franc Loan multiple times, even on national TV. But I guess nobody was really listening, you know? Everyone was too focused on how low the interest rates were, which was clearly the only thing that mattered at the time. Who honestly cares about a few warnings when money is cheap?
Casey Cook10 Casey Cook10 Active Member
77 messages
joined May 2024
#299 ·
Richard Taylor3 said:Well, look, the Banks actually took the government to international arbitration courts. And since those courts would have almost certainly ruled in favor of the banks, the government ended up settling with them behind closed doors—it was all kept strictly confidential. I mean, why else would they keep it secret? And if you ask me, who do you think covered the losses caused by the government's conversion law? It wasn't just magic; someone had to pay the bill.

Well, maybe go settle that with the government then, since they seem so willing to play ball with international arbitration while ignoring our own US and EU legal systems...
I guess we should just vote for someone who might actually make us less dependent on the big banks...
They should just go ahead and publish that settlement... along with the deals for JT, ExxonMobil, and everything else for all we care...
Richard Taylor3 Richard Taylor3 Member
12 messages
joined Apr 2023
#300 ·
Casey Cook10 said:Well, maybe go settle that with the government then, since they seem so willing to play ball with international arbitration while ignoring our own US and EU legal systems...
I guess we should just vote for someone who might actually make us less dependent on the big banks...
They should just go ahead and publish that settlement... along with the deals for JT, ExxonMobil, and everything else for all we care...

Look, I don't have anything to settle with the government—it's enough for me just to vote against the Democratic Party.

You must log in or register to reply here.

Log in Register

🔗 Similar threads