#1 ·
It seems like everyone has suddenly rushed toward the US lately, hasn't it? I have to say, seeing this surge for Chime specifically makes me really happy. Out of all the fintech services out there, they’ve managed to become one of the biggest players—if not quite the largest. 👍
Chime is honestly a fantastic service. I’ve been using it for my Apple Pay transactions, and so far, everything has been seamless. It would be great if they offered USD support when I head back to the States, though I realize that might be a stretch since they don't even carry the local currency in much larger markets yet. But hey, you never know, right? 🍿
WSJ.com
Chime is honestly a fantastic service. I’ve been using it for my Apple Pay transactions, and so far, everything has been seamless. It would be great if they offered USD support when I head back to the States, though I realize that might be a stretch since they don't even carry the local currency in much larger markets yet. But hey, you never know, right? 🍿
It looks like N26 has already reached out to the Federal Reserve—they're clearly making their move to enter the American market.
Once a bank from another EU member state sends over a passport notification, they can step right in and start offering services here in America immediately. Isn't that efficient?
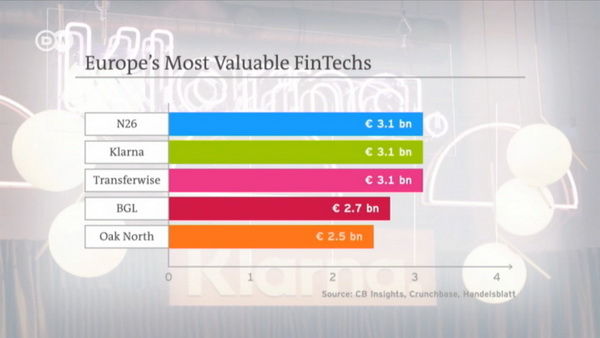
It looks like Revolut isn't the only player eyeing an expansion into the American market. According to reports from the Wall Street Journal, its biggest rival—the Berlin-based N26, which stands as one of the most valuable mobile banks in Europe—has already gone a step further by making several strategic moves to prepare for its entry into the US. Is the competition about to heat up even more?
With the buzz surrounding Revolut’s announcement—one of the two biggest mobile banking giants in Europe—about entering the American retail market this summer to go toe-to-toe with our top ten major banks, there is another player making quiet moves. N26 has already "notified" the Federal Reserve, effectively checking off all the boxes needed to start offering services here. While N26 is already up and running in Canada, they haven't shared any specific details regarding further expansion plans just yet. Could we be seeing more competition on the horizon?
When we reached out to the Federal Reserve regarding mobile banking apps and other fintech players planning to enter the American market, they pointed us toward the list found under the "passport notification." It’s quite an extensive roster, featuring over 170 banks from all corners of the globe that are authorized to offer services here thanks to the European banking passport. Looking through the names, you see some of the absolute heavyweights of the global financial world. We're talking about major American institutions like Wells Fargo, Morgan Stanley, and JPMorgan Chase, alongside international giants such as the UK's HSBC, the Netherlands' ING, Germany's Deutsche Bank, and France's BNP Paribas. The list even stretches across the Pacific to include Japan's Mizuho and China's Bank of China. Interestingly, even Rakuten Bank—linked to one of Japan's largest internet conglomerates—is included on there. Isn't it fascinating to see just how much global competition is poised to step onto our shores?
Most of the banks listed here are primarily focused on massive institutional investments and government projects rather than true retail banking. When we talk about retail banking, we’re really talking about everything from basic checking accounts to consumer loans—and if you broaden the scope to commercial banking, that includes services for small business owners too. Interestingly, though, looking through that Federal Reserve list, we actually found Chime, the mobile banking platform based out of Berlin.
A financial institution from another European Union member state can start providing services directly here in the States as soon as the Federal Reserve receives a passport notification detailing exactly which services they intend to offer. The Federal Reserve publishes these notifications publicly, meaning the institution doesn't need to go through any additional permit processes. Isn't that a streamlined way to handle things?
Chime, which boasts a market valuation of $2.7 billion and has secured backing from heavyweights like Allianz and Tencent, has already signaled its intentions to the Federal Reserve. According to recent filings, they are looking to establish a foothold in the American market by offering checking accounts and accepting deposits. On top of that, they're eyeing the lending space—including consumer loans—alongside various other payment services. Isn't it interesting to see how quickly these fintech players move to shake up the traditional banking landscape?
According to the Federal Reserve, there is currently only one player from another European Union member state operating in our domestic market that focuses primarily on digital banking—specifically those services you can sign up for directly online—and that would be the Finnish lender Ferratum. As for the other banks, the Federal Reserve notes they are currently in the process of developing their digital offerings. The central bank also took the time to explain why local financial institutions have been paying such close attention to the news of Revolut’s arrival, especially since Revolut announced plans to integrate USD into its app. It really comes down to this: citizens already have the right to open an account in any bank within the European Union and receive their salary there. With new players like Revolut and Chime entering the fray, wouldn't you agree that making that entire process completely seamless is the logical next step?
"The ability to freely open transaction accounts abroad without needing prior approval from the Federal Reserve—which used to be required only if the account was opened for specific designated purposes—was actually implemented back in January 2011. The Federal Reserve maintains that an employer resident here can pay a resident employee exclusively in USD, provided the payment is being made into an account held at a foreign-based bank," according to statements from the Federal Reserve.
The Federal Reserve further clarifies that while special permits aren't necessary, all foreign players operating within the US must still abide by American laws. They noted that these institutions must comply with the Law on Credit Institutions, specifically regarding consumer protection (Articles 300-312), along with all other relevant regulations.
"Even though supervision of such institutions falls under the regulator of their home country, if the Federal Reserve spots any illegal activity, we notify the appropriate authority in that EU member state's home country. We can also request mediation through the European Banking Authority and have the power to mandate preventive measures," the Federal Reserve concluded.
WSJ.com