CheckEmoji Community · the emoji forum
🏠 Home 🆕 What's new ❓ Unanswered 🔥 Popular 📡 RSS Members 👥 0 online log in · register
Home › Michelle Bennett5 › Posts

Posts by Michelle Bennett5

171 posts shown.

Omicron variant in Coronavirus ·
Sarah Ross21 said:I have no idea where you're getting your data, but it's the exact opposite of everything I've read. That's not what the epidemiologists were saying, either. Unvaccinated people are much worse "breeding grounds" for mutations than those who are vaccinated. It's basic logic, isn't it? They just took some ingredient, whatever they want to call it!

That’s why they came up with that "do it for others" slogan. Except the logic is a bit too transparent for most people to actually buy.

If I’m reading this slogan right, the whole "get vaccinated..." part is aimed at the people who actually need the shots, not the ones who already have them.
Omicron variant in Coronavirus ·
Linda Harris59 said:I never said that.

Let me be perfectly clear about what I actually wrote: the virus has a much higher potential for mutation and poses a greater threat to the community when it takes hold in an organism with a weakened immune system and no existing antibodies.

In vaccinated individuals, there is a significantly lower probability of mutation occurring. It's basic math—there is less virus present and it stays in the system for a much shorter window of time.

So, here’s my take: mutations in vaccinated people are way more dangerous. In the unvaccinated, they just survive every single mutation the virus throws at them. So, if any truly nasty ones actually manage to break through, they’ll just get buried under a massive pile of harmless ones anyway. Makes sense, right? Or am I just talking to myself here?
So, here's the thing. Among the vaccinated, you're only going to see those super-mutations—the kind that can actually be carried by the vaccine itself. And genetically speaking? They’re a total bullseye.
So, here’s the logic people love to throw around: the more people you vaccinate, the higher the chance you're basically rolling the dice for some massive supermutation to pop up. Makes sense on paper, right? Or does it? I don't know. It's one of those "common sense" arguments that sounds deep until you actually sit with it for a second. Just a thought.
Why am I getting blocked from so many websites? in IT Support ·
Which Windows version are we talking about? And what browser?
I used to deal with this exact same nonsense back when I was stuck using Internet Explorer, so now I just stick to Google Chrome.
Issues shrinking a volume on Windows 10? in IT Support ·
Carol Harris9 said:I am honestly at a complete loss here; I simply cannot get this to work, which is incredibly frustrating because I have successfully resized partitions on five or six other laptops without a single hiccup. On my current machine, I’m looking at a C: drive with 90 GB and a D: drive with 150 GB, both running the exact same version of Windows.
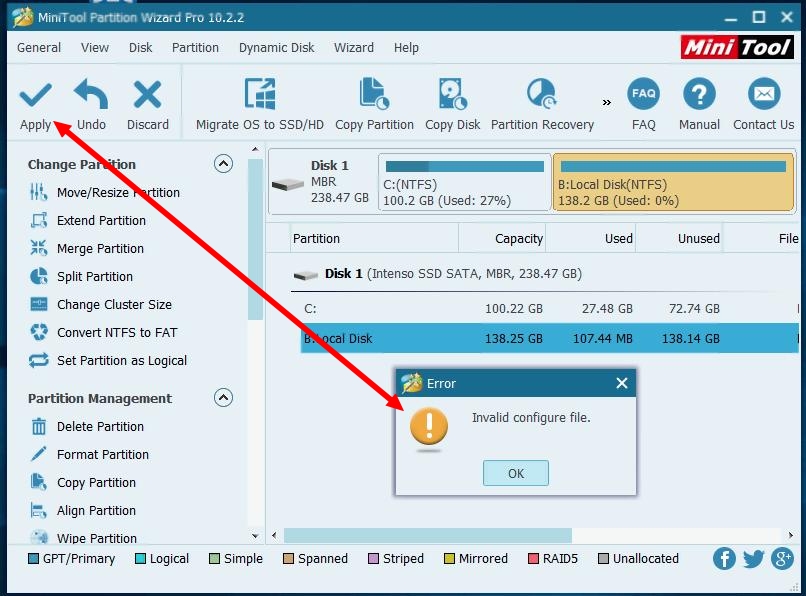
I attempted to resolve this using MiniTool Partition Wizard, but it just refuses to cooperate. My plan was quite straightforward: expand the C: drive to 100 GB and let the D: drive occupy whatever space remains.
I have attached an image below showing exactly what happens immediately after I click the Apply button.
imageopen source screen capture

Does that have anything to do with it? The screenshot shows the C: and B: partitions.

(Shouldn't it be D:?)
Issues shrinking a volume on Windows 10? in IT Support ·
Carol Harris9 said:My brother has been running a laptop with a 60 GB C: partition dedicated to Windows 10, and honestly, it’s been performing flawlessly for over five years now.
The reason I’m so adamant about having two separate partitions is quite simple: if the operating system ever hits a snag and requires a complete reinstall, I want to ensure my precious data on the D: partition remains perfectly safe and untouched.

Look, if you're actually stressing about stuff like that, and you're running a desktop (not a laptop), isn't it just better to slap in a second physical drive for your data? Just put your D: partition on its own separate disk and call it a day.
Two different VPNs or something else? in IT Support ·
What’s this deal with the "1000 EUR" thing? Is that just the specs for a router you could flash with ExpressVPN?
When you set up the software, once the VPN is installed, a new virtual network adapter pops up on your computer. It acts like it was physically plugged in, but really, everything routed through that connection is being tunneled through the VPN.

That way, you can actually run a VPN inside a VPN—like having a second VPN endpoint, say Cisco AnyConnect, nested right inside ExpressVPN.

Once the connection hits the USA, the rest of the world sees your ExpressVPN IP address. The catch? If ExpressVPN has a bad reputation, some routers might block the connection entirely because they recognize the IP range belongs to a specific organization.
Two different VPNs or something else? in IT Support ·
IP addresses aren't just random numbers; they're tied to specific locations
If you're trying to fake being in the UK, you really need to find a VPN that actually has servers physically located there to mask your traffic
Sure, you can hide your actual IP address while sitting here in the States, but that won't make it look like you're calling from London. To pull that off, you'll need a VPN with a UK presence
Two different VPNs or something else? in IT Support ·
So you just leave your PC running back in the States with TeamViewer active,
then you hop on from wherever you are using TeamViewer and run Cisco AnyConnect directly through the remote connection.
Overdrafts and negative balances: What's allowed? in Banking, Insurance & Loans ·
vividraven79 said:That’s a pretty colorful way to describe someone being crude... if I'm following you correctly, you're essentially calling them incapable of looking after their own interests?

Let's try this... suppose by some freak accident I rose to power and passed a law banning negative balances, decreeing that all debts must be refinanced over one to five years at the debtor's discretion... I can almost guarantee you'd see protests erupting across the entire country.

You can't just pull a hard 90-degree turn at full throttle; any boat would capsize immediately.
You have to take it slow. You have to work the media, shape the narrative so people actually believe they’re coming out ahead instead of losing out. There's an entire field of study dedicated to crowd control and mass psychology, specifically how to get people to act exactly how you want them to. And honestly? We’d want it to be fair and actually beneficial for them too, because at the end of the day, that's what serves our own interests best, right?
Overdrafts and negative balances: What's allowed? in Banking, Insurance & Loans ·
vividraven79 said:If you’re asking me, I’d cap credit card installments at 12 months and offer everyone the chance to roll their overdraft balances into a structured loan over 2 to 5 years—using standard commercial interest rates, of course. And just like you said, any overdraft exceeding $500 should be pushed out to 90 days... after that, you can go ahead and take out a formal loan.

But your average American doesn't know how to function without living in the red... and they’ll scream at Chase or Bank of America because the bank won't let them overdraw, or if they only allow an overdraft of "two paychecks," they end up complaining about the interest later on.

The typical American will just grab the higher-tier package because while the basic one covers 100% of their salary, the premium version offers up to 300%, plus a higher revolving limit on $13

And then, once the whole thing comes crashing down, they start some "Debt Relief Association" support group.

That’s why we have regulators in the mix—rules actually designed with some common sense and fairness to look after people who clearly can't look after themselves.

Basically, sheep need sheepdogs to make sure they don't wander straight into the wolves' mouths.
The sheep aren't usually complaining about the dogs; it's always the wolves whining that the sheepdogs are "restricting the freedom" of the flock.
Overdrafts and negative balances: What's allowed? in Banking, Insurance & Loans ·
Paul White9 said:A negative balance is perfectly fine if you’re hovering near zero and, say, $117 (assuming you weren't checking), like when you fill up your tank with gas for $133 and instead of the card getting declined, it actually goes through, leaving you at -$17. It’s much more elegant than running into serious trouble while you're traveling.

The crowd complaining about being in the red—people who act like a negative balance is some huge tragedy—just don't get it. They basically took a loan upfront. Now they have to pay it back out of their own paycheck, otherwise they'll be stuck in the red forever, drowning in interest rates that are anything but small. So, that group constantly whining, "Ugh, I'm always in the red," doesn't realize they are essentially spending money they haven't even earned yet. And how am I supposed to dig myself out if my income is low? First off—did you actually *need* to go into the red this month? If it was for life-saving medication? Yes. If it was for a night out with friends or some new clothes? That's on you. Second, why not just tighten your belt for a few months to pay it off? Treat it like you're paying down a car loan or something. Self-discipline, people. Regardless, you’ll come out ahead if you manage to swing from +$1333 to 0 every single month. Instead, you're going from 0 to -$1333, plus extra interest every month, sinking deeper and deeper into the hole.

And why on earth should the government bail these people out? Sure, maybe convert those negatives into standard loans. But interest-free? Why? What's the logic behind giving these people a free pass? By that logic, I'd just intentionally run up a negative balance to get an interest-free loan rather than taking out a legitimate loan and actually paying interest.

That's a bit of a stretch, don't you think? Sounds more like a freak occurrence than an actual rule of thumb.
Who actually travels without a few hundred bucks in cash tucked away, especially if their bank account is sitting at zero?

People used to be way better at managing their money back in the day.
Like, my parents—whenever they got their paychecks, they’d pull the cash out of the bank and sort it into envelopes based on what last month's bills looked like (electricity, rent, the grocery store, food, gas, etc.), and only then would they touch whatever was left over.
Overdrafts and negative balances: What's allowed? in Banking, Insurance & Loans ·
I don't even know where to start with this one. Just... wow. Is anyone else seeing this? Honestly, I feel like I’m losing my mind a little bit. It’s just one thing after another lately, isn't it? You think you've seen the peak of absurdity, and then—boom—something else hits the fan. Does anyone actually believe this is working? Like, really? It feels like we're all just circling the drain while pretending everything is perfectly fine. It's exhausting. Truly. I could go on about how ridiculous the whole situation is, but what's the point? We've been here before. Same circus, different clowns, right? Anyway, just my two cents. Or maybe just my two cents plus tax. Whatever. kaže:
So, let me get this straight. Someone goes out of their way to borrow money they clearly shouldn't have, and now the solution is to hand them an interest-free loan for two years just so they can pay back what they already owe? Seriously? What, are the rest of us sitting here with our savings just being complete idiots for playing by the rules?

That’s just a side note, really. The whole point was to push for getting rid of those negative balances entirely and actually fixing the debt that's already sitting there.

The whole point here is just getting the economy back on its feet, right? We’re basically trying to convince everyone to actually open their wallets and deal with those red numbers instead of just staring at them.

So, apparently, they're dropping something like $70 million a year just to cover interest on those negative rates. Yeah. Just... gone. Poof. Does anyone actually think that's a smart way to run things? It’s just money down the drain, isn't it?

Honestly, isn't it better for the government to just let that money flow through consumer spending? I mean, isn't that where the actual productivity happens? Why sit on it when you could be moving the needle?
Paying off these negative interest rates? It’s just dead capital. Honestly, what’s even the point? You're basically throwing money into a black hole for nothing. Why tie up your cash when it's just sitting there doing absolutely zero work? It feels like a total waste of resources. Is it even worth the effort? Probably not.
Overdrafts and negative balances: What's allowed? in Banking, Insurance & Loans ·
this is honestly hilarious

at this latest meeting between big banks and the government, everyone’s out there shedding crocodile tears over how the poor Americans can barely make ends meet, yet they're still perfectly fine charging interest on that very poverty

isn't it obvious? you only pull money from the red once when you first dip into your overdraft, but after that, you're just living off whatever hits your account each month—only to spend your whole life paying the bank interest just because you hit that negative balance once (and haven't climbed back out)

just turn all those existing overdrafts into zero-interest loans—maybe use some federal relief funds to clear them out—and then just deduct them from monthly income over 24 installments

as for the folks who truly can't make it, let the social services handle that

ELIMINATE the overdrafts. if someone actually needs emergency cash, they can take out a short-term loan

supposedly there are 840,000 accounts in the red, and if you look at the average overdraft size, $2333
with an average interest rate of 8%
the result is 470 MILLION dollars

that much money leaves the hands of the struggling American people EVERY SINGLE YEAR just to cover interest on totally UNNECESSARY debt

what kind of logic is the government using when they claim to be the protectors of their own citizens?
Overdrafts and negative balances: What's allowed? in Banking, Insurance & Loans ·
Richard Campbell10 said:Look, if they offered me a way to stretch it out over, say, 24 monthly installments, I’d sign that deal right this second. I guess I'll just have to see how things play out and then... well, I'll figure out some way to make it work somehow.

So this makes it sound like your debt is their headache instead of yours?
In the banking world, your balance has to be massive before anyone actually starts losing sleep over it.
Overdrafts and negative balances: What's allowed? in Banking, Insurance & Loans ·
Richard Campbell10 said:True enough, but I'm not going to lose sleep over it. I already applied for and secured a loan where the interest rates are pretty much right at the legal limit (Chase), and since my paycheck hits my account regularly and I use them for everything from loans to basic banking, I really don't think they'll give me any trouble.

So, let me get this straight... you're $13,500 in the hole, carrying an 8% interest rate?
You've already burned through their money ($13,500) and gotten zero benefit from it, yet you'll be stuck paying that 8% on the overdraft forever. That's $1,080 a year just disappearing.

Banks love nothing more than having a guaranteed, lifelong stream of income from their clients—especially when they have no clue how to actually invest capital. Like, the Fed is basically telling everyone that global interest rates can dip into the negatives. Usually, banks actually end up PAYING people to hold their cash just so they don't lose even more ground.
Overdrafts and negative balances: What's allowed? in Banking, Insurance & Loans ·
Richard Campbell10 said:I mean, let’s be real—everyone sitting on a negative balance is going to get hit with this, myself included. I’m staring down a $13,500 deficit right now. If they scrap the current terms and force us into a 12-month repayment plan, we're looking at $375 plus interest. Honestly? Where am I even supposed to find that kind of cash?

That's basically a gourmet meal for the bank.

Banks absolutely love it when you're teetering on the edge of financial ruin—just grinding away at interest payments without ever actually touching the principal balance.

It's like their version of a fever dream.

In your situation, if we're talking actual logic, you might be better off grabbing a long-term loan from a different lender, like Wells Fargo or something, just to get a monthly payment that doesn't leave you starving.
Kill that overdraft immediately and just deal with the new loan payments instead.
Or, I don't know, sell something you own to get some quick cash?
Look, it isn't pretty, but you did this to yourself.
melloweagle28 said:I absolutely disagree. I am the complete opposite. I avoid any merchant that doesn't take credit cards whenever possible. To me, using Cash is nothing more than a necessary evil, and supposedly a fantastic carrier for germs, cocaine, and urine.🙂

I despise installment plans, and while I haven't needed them yet, it's unrealistic to assume I'll always be in a position to avoid them. When money runs short, an installment plan is effectively an interest-free loan.

Hey, newsflash: banks charge a FEE for every swipe through a card reader.
Around 2-3%.

Supposedly, that fee comes out of the merchant's pocket, right?
BUT!!!!!
The seller obviously just builds that cost right into the price tag, so you're actually the one footing the bill!

And like I said, those "interest-free" installments aren't really free—all those extra costs are baked into the monthly payment from day one.

Paying with straight-up Cash is the only way to get the actual lowest price.
(Not that the big banks and their little minions will ever admit that.)

Just so we're clear, if you want to avoid confusion about using Cash, getting an official receipt is 100% fine.
melloweagle28 said:I honestly don't know how other banks handle things.

But I figured I’d just get it sorted now so it's ready when I actually need it. That happened twice. We're talking about Chase here. So, I brought in my employer verification or whatever document was required to activate installment payments on the Visa card linked to my existing checking account. The tellers told me they'd approve an overdraft for me. I told them no, I don't want an overdraft. Then they claim that if I don't take the overdraft, I can't have the installment plan either.

Installment plans are a total scam. You never truly know how much debt you're actually drowning in or what you actually have left to spend.

If you ask me, the smartest move is just hitting the ATM, grabbing Cash, and paying the full amount upfront. If a vendor is running a real business, they might even give you a discount for paying in full. That’s where the actual savings happen.

You really have to force yourself into a position where you actually have the funds available. Paying high interest rates is a massive waste compared to just building up a decent pile of cash.

All this stuff—installments, loans, overdrafts, interest—it’s just a way to bleed you dry.
Every system loves having a working class to exploit—a helpless mass with nothing to their name, capable of nothing but working themselves to death for the people who own the means of production.
mistybadger2 said:The guy spelled it out perfectly. Most banks set everyone's limit to zero and swapped the permitted amount for whatever was considered the standard limit back before the decision at end of 2017.
Basically, they pulled the same shady stunt on everyone.
The few people who caught onto the game—the minority—negotiated a legitimate permitted overdraft. Everyone else is stuck dealing with the unpermitted mess.
Most people didn't realize that behind all this jargon, they were essentially getting fleeced for an extra 30%.
Meanwhile, that snake of a Governor has been smirking about it for four years.
You really have to watch out for these banking bottom-feeders. Given how easily Americans can be misled and the sheer corruption in our government, these guys have found themselves a gold mine that most criminals could only dream of.

So you're telling me... if I have the exact same amount of debt as last month when I was still within my PERMITTED limits, I suddenly wake up next month and find myself in the SILENCED zone?
And with a way higher interest rate too?
All without getting a single written notice or anything?
Jack Cook7 said:Ugh... inertia is such a nasty habit. I had this coworker show up to the office one day looking totally wrecked. What happened? His account got frozen by the bank because he was $6.25 (if I remember right) overdrawn, so he couldn't even pay for gas. Like, seriously? Wait, what's your overdraft limit? $300, he asks, laughing. So you blew past your limit to $306, and now you're shocked the bank locked you out? And what's the interest rate on that? Probably something like 9%.

People just get used to that miserable negative balance and stop paying attention entirely.

You should treat an overdraft like scuba diving—you take a dive, but after a minute or two, you've gotta come back up to the surface (sea level >= 0)

Basically, a negative balance should be a BUFFER, something to jump into if you need to, but you have to drain it. For example, next month they cut your limit in half to force you to pay it back, then the following month cut it in half again, and only once you hit zero can they give you the full amount back.

That’s how the government should protect citizens via law. After all, isn't the whole point of the state to exist for the people?

I can't wait for Level 5 AI to become a reality. Then maybe we can apply it to the banking system, automate lawmaking, and finally everything will be fair.