I honestly don't think that's even a thing. You can't just walk up to a Chase ATM right now and deposit cash straight into a Zalando account.
You should probably check the Chime website to see if they even offer that service. From what I can tell, in Germany they only let you deposit via partner retailers—they don't mention ATMs at all. Besides, they hit you with a 1.5% fee for deposits anyway.
JPMorgan Chase just automatically approved an overdraft for me barely a month after my first paycheck hit. Since then, they’ve just kept renewing and extending it. Nobody ever even bothered to ask what kind of contract I had.
Don't sweat it. Banks aren't going to scrap overdrafts. Even if interest rates drop, they're still going to rake in way more profit from those than they will from any standard loan.
Kevin Morris12 said:I’m looking at my JPMorgan Chase app right now, and they refer to my allowed overdraft as "Available Overdraft Limit." I actually picked this specific amount myself a few years back and signed some paperwork at the branch to have it approved for a 12-month term. Every eight months, like clockwork, they just send me a notification saying the limit has been extended for another 12 months (so, for example, it stays valid from August 12, 2021, through August 12, 2022). Since I first used that overdraft about xy years ago, it always seems to trigger right on that eighth month. So, here’s my question: would they technically consider this a "tacit" overdraft, or does that even make sense? Does JPMorgan Chase even have a concept of tacit overdrafting? 🤔
That's pretty much all they've got. Honestly, I don't get how you can call it "silent" if you have to walk into a branch and ask for it. For instance, Bank of America automatically kicks an overdraft into gear the second your first paycheck hits the account, no questions asked—that's what I'd call a silent overdraft.
They’re allowed to, and they do it. They don't even need your permission anymore.
"Processing your data through the DOR system is based on our legitimate interest—as well as the legitimate interest of all users (per Article 6(1)(f) of the Regulation)—to evaluate whether clients can actually pay back what they owe. This helps us minimize or avoid bad loans and overindebtedness, which is just part of managing credit risk, one of our main regulatory requirements. ... An inquiry into the DOR system can only be made in these specific scenarios: a) before signing a new credit or financing agreement or when modifying an existing credit or financing agreement b) during periodic monitoring and credit risk assessments for clients who already have an active credit or financing agreement."
Harold Anderson3 said:I originally kicked off this thread back in May of last year. The garnishment hasn't actually hit my paycheck yet, but I’m starting to worry that avoiding it might be a lost cause because 1. JPMorgan Chase is coming after me for $333 over the next three months. 2. My primary bank (think Wells Fargo) just announced they’re dropping my overdraft limit from $10,000 down to $2,600 starting next month. 3. I still have to cover my basic monthly bills and, you know, actually afford to eat. I managed to get a four-month loan moratorium, but honestly, given how things are looking, it feels like a temporary band-aid on a much larger problem. I’ve already started looking into what my move will be once the legal seizure officially kicks in. My take-home pay is roughly $4 $0.00, so if I set up a protected account through the IRS, I’ll basically be living on two-thirds of my check from then on. It’s a bit daunting to think that this whole cycle could drag on for years...
If your paycheck is still hitting that account, why not just talk to them? See if you can negotiate an extension on that overdraft limit. Even if they do cut it, they're legally required to let you pay off the difference over 12 months, so you won't get hit with one massive bill all at once.
If things go south and you end up facing collections or a frozen account, you might want to look into consumer bankruptcy protections.
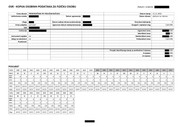
Here’s a look at what that famous credit report actually looks like for anyone wondering. It’s basically identical to the old HROK report—you can see all your loans, any overdrafts on your checking account, and those revolving credit card balances.
On the DOR report, if you've stayed on top of your bills and never missed a payment, all you'll see is your SSN and which financial institution pulled your info.
If I caught his drift, he’s paying off some other loan, so the admin just blocked that. For the leasing part, they basically just asked him how much he still owes on that existing credit. From what I could dig up online, you pay the leasing through monthly installments. The only thing I didn't realize was that even with leasing, you still need approval from Chase. 😢 Since the leasing company hits you with a 1-1.5% processing fee, a straight cash loan actually seems like a better deal to me—at least you aren't getting slapped with that extra fee.
Aha, figured as much. 👍 Do you happen to know how they calculated your creditworthiness? Like, is the monthly payment capped at maybe a quarter of your paycheck or what? And I'm assuming with leasing there's no need to deal with a notary for anything?
Anyone got some recent experience with consumer leasing? I'm curious how these leasing companies actually calculate creditworthiness these days. What kind of paperwork are they demanding to get an approval through?