CheckEmoji Community · the emoji forum
🏠 Home 🆕 What's new ❓ Unanswered 🔥 Popular 📡 RSS Members 👥 0 online log in · register
Home › Society › Economy › Banking, Insurance & Loans › Chime: My experience so far

Chime: My experience so far

Started by Kevin Morris12 · · 👁 8 views · 297 replies

📡 Subscribe to replies

Participants Kevin Morris12boldcanyon14electricbadger89Dennis Williams40Karen Cook7analogjackal11nimblefox14Jeremy Rivera45velvetbear372Roger FowlerJames Kern2Kevin Lee7frozengull94Michelle Davis15Gary Bakermellowhawk33Scott Sanders5ironcyclist58William Barrett7Casey Torres10Edward Evans7Joseph Martin10darkmaker94velvetorca4 …
Kevin Morris12 Kevin Morris12 Active MemberOP
230 messages
joined Mar 2020
#21 ·
The last time I checked in, about a month ago, the color was definitely blue on my end. Honestly, I agree—the old design was much more appealing, but they probably overhauled it just to distance themselves from the launch of "Chime You." Whatever the reason, I’m not planning on ordering one until they finally roll out Apple Pay support for it. There’s really no point until then, right? 🤷
velvetbear372 velvetbear372 Active Member
56 messages
joined Aug 2018
#22 ·
When is Chime planning to launch in the US?
Roger Fowler Roger Fowler Active Member
90 messages
joined Sep 2022
#23 ·
Karen Cook7 said:Nah, no way.
Now they’re looking to tweak the bankruptcy laws just so they don't "accidentally" receive anything into a foreign account—even if you have a local IBAN—strictly so they can get their hands on your money.

They can take that idea and shove it, honestly; isn't it obvious this will just drive everyone straight toward offshore accounts?
James Kern2 James Kern2 Member
24 messages
joined Sep 2020
#24 ·
I’ve been doing some digging and looking into Chime lately... it seems like maybe the "safest" bet if I were to pair it up with something like Revolut

especially since they actually have an established presence and local offices over here, so you can actually rely on them when things go sideways

just waiting to see when they officially launch their full services in the States to decide if making the switch is even worth the hassle... for now, I'm just stuck reading about it online...
Kevin Lee7 Kevin Lee7 Member
29 messages
joined Sep 2019
#25 ·
Look... even the big banks aren't 100% foolproof... I suppose you just use some sort of combination until something better comes along...
Chime seems to be expanding rather slowly for some reason...
James Kern2 James Kern2 Member
24 messages
joined Sep 2020
#26 ·
Out of all these fintech players, Chime feels like the most secure option to me... though I could be completely off base here.

The fact that they aren't expanding at breakneck speed actually works in their favor... it suggests they’re more meticulous, maybe even perfectionists about their rollout. They probably aren't just rushing headlong into chaos without thinking things through first.
frozengull94 frozengull94 Member
37 messages
joined Aug 2021
#27 ·
Also, I’m just sitting here waiting on everything from Chime...
To me, they feel way more secure than Revolut..

Maybe I’ve got it all wrong..

I should probably add, those people pushing $17 just seem like... I don't know, window dressing. Purely superficial..
Hell $17 if it's actually a legitimate company. Look, I want a real professional relationship, not some platform designed for buying $2 junk online or splitting a bill between girlfriends on a Saturday afternoon when they're heading out to some birthday party..
Kevin Lee7 Kevin Lee7 Member
29 messages
joined Sep 2019
#28 ·
frozengull94 said:Also, I’m just sitting here waiting on everything from Chime...
To me, they feel way more secure than Revolut..

Maybe I’ve got it all wrong..

I should probably add, those people pushing $17 just seem like... I don't know, window dressing. Purely superficial..
Hell $17 if it's actually a legitimate company. Look, I want a real professional relationship, not some platform designed for buying $2 junk online or splitting a bill between girlfriends on a Saturday afternoon when they're heading out to some birthday party..

I wouldn't go that far... people are naturally skeptical of new tech... these $17 things are just pure advertising, much like what you see from Chime, Chime, Curve, and everyone else... someone pays for ads, and then certain people just become walking advertisements.
I personally haven't had a single issue, even after moving significant amounts through them.
frozengull94 frozengull94 Member
37 messages
joined Aug 2021
#29 ·
The real issue here is that we’re living in the middle of nowhere...
It’s like they treat us as some backwater outpost on the edge of the map, way over the ocean. It doesn't even matter that we're part of the Western alliance or whatever...
Plus, our market is just too small for anything significant to actually take root...

I mean, honestly, when you realize half the people in this country barely even touch the internet, let alone...
😁

A few of you guys are certainly being some very enthusiastic brand ambassadors for this company...
I assume the kickbacks make it worth your while...
Michelle Davis15 Michelle Davis15 Active Member
53 messages
joined May 2007
#30 ·
James Kern2 said:Out of all these fintech players, Chime feels like the most secure option to me... though I could be completely off base here.

The fact that they aren't expanding at breakneck speed actually works in their favor... it suggests they’re more meticulous, maybe even perfectionists about their rollout. They probably aren't just rushing headlong into chaos without thinking things through first.

Look, I’m all for tech advancements, I really am, but these digital banks don't actually offer any real advantage over traditional institutions right now—aside from maybe having icons that look a bit more modern. Take Chime, for example. What are they actually bringing to the table?

Offering some fancy little categorized breakdown of monthly expenses by type? Honestly, it’s laughable. It has absolutely nothing to do with actual banking.

There’s nothing revolutionary about this. Honestly, that’s the real reason why they’re dragging their feet on replacing those ancient plastic credit cards. They just aren't offering anything better or more efficient than what we already have. Why bother rushing the process if there's no actual upgrade?

What actually makes a digital bank worth your time? It’s pretty straightforward if you think about it. You want a platform that lets you send money to any account anywhere in the world instantly without jumping through hoops. You want rock-bottom transaction fees. You want access to quick credit with reasonable interest rates. And honestly, you should be able to hit just about any ATM on the planet to grab cash without getting gouged on fees. It’s as simple as that. But here’s the kicker: so far, not a single digital bank out there actually delivers on all of that.
Kevin Lee7 Kevin Lee7 Member
29 messages
joined Sep 2019
#31 ·
frozengull94 said:The real issue here is that we’re living in the middle of nowhere...
It’s like they treat us as some backwater outpost on the edge of the map, way over the ocean. It doesn't even matter that we're part of the Western alliance or whatever...
Plus, our market is just too small for anything significant to actually take root...

I mean, honestly, when you realize half the people in this country barely even touch the internet, let alone...
😁

A few of you guys are certainly being some very enthusiastic brand ambassadors for this company...
I assume the kickbacks make it worth your while...

I did it for a couple of beers, really... but since it actually helped me, I figured why not share it with others... I paid for my own card delivery and didn't even use a referral code$17... so why shouldn't I offer it up to everyone else?

We live in the kind of country we live in... but at least the internet gives us access to all sorts of tech

@Michelle Davis15
-it's free
-best exchange rates and basically the only way to get certain currencies easily
-fee-free withdrawals up to $250 (for instance, if someone comes from Mexico with Pesos into an account with $150, a major bank like Chase might charge them $30 in fees, whereas Revolut keeps the loss to maybe $10-$20)
-live tracking and the ability to auto-buy any supported currency
-virtual card option for online shopping... you can just delete it afterward so you don't have to worry about whether a site is legit
-setting card limits... you set a max spend of $10 and don't have to stress about someone overcharging you
-ability to freeze the card if it gets lost
-geolocation security features
-free PIN changes

But sure... go ahead and ignore all those advantages
James Kern2 James Kern2 Member
24 messages
joined Sep 2020
#32 ·
Michelle Davis15 said:Look, I’m all for tech advancements, I really am, but these digital banks don't actually offer any real advantage over traditional institutions right now—aside from maybe having icons that look a bit more modern. Take Chime, for example. What are they actually bringing to the table?

Offering some fancy little categorized breakdown of monthly expenses by type? Honestly, it’s laughable. It has absolutely nothing to do with actual banking.

There’s nothing revolutionary about this. Honestly, that’s the real reason why they’re dragging their feet on replacing those ancient plastic credit cards. They just aren't offering anything better or more efficient than what we already have. Why bother rushing the process if there's no actual upgrade?

What actually makes a digital bank worth your time? It’s pretty straightforward if you think about it. You want a platform that lets you send money to any account anywhere in the world instantly without jumping through hoops. You want rock-bottom transaction fees. You want access to quick credit with reasonable interest rates. And honestly, you should be able to hit just about any ATM on the planet to grab cash without getting gouged on fees. It’s as simple as that. But here’s the kicker: so far, not a single digital bank out there actually delivers on all of that.

Personally, I think having something like Apple would be great... though if our local banks—like Chase, for instance—actually bothered to modernize, I wouldn't even feel the need to mess around with fintech companies myself...
nimblefox14 nimblefox14 Member
10 messages
joined Jul 2019
#33 ·
Man, I am seriously losing it today... I’m sitting here waiting on a deposit to hit my account. I know it usually lands around 10:00 or 10:30, but nothing. No notification, no ping, nothing.
I try opening the app, but I'm logged out. I punch in my username and password, and the thing just spins for like thirty minutes before doing absolutely nothing. Try again? Same exact thing. I even tried logging in via my computer, but it just keeps loading and then hits me with a 500 error.
Checked both of their profiles on X, and they haven't said a word. I finally tried the app again after half an hour, and *that's* when it finally pops up saying they're having scheduled maintenance. Like, wtf, get it together.

Sen fra my iPhone using Tapatalk
frozengull94 frozengull94 Member
37 messages
joined Aug 2021
#34 ·
So, you know, just like those old torrent sites, Kickass and stuff like that...
😁
Kevin Lee7 Kevin Lee7 Member
29 messages
joined Sep 2019
#35 ·
Crashes seem to be pretty frequent lately... I suppose these companies are still just getting their footing—let's give them some breathing room, especially since they're offering the service for free anyway.
Kevin Morris12 Kevin Morris12 Active MemberOP
230 messages
joined Mar 2020
#36 ·
A lot of people are probably going to be pretty frustrated with Chime once they realize they can't just top up their account using a card.
Michelle Davis15 Michelle Davis15 Active Member
53 messages
joined May 2007
#37 ·
Kevin Lee7 said:I did it for a couple of beers, really... but since it actually helped me, I figured why not share it with others... I paid for my own card delivery and didn't even use a referral code$17... so why shouldn't I offer it up to everyone else?

We live in the kind of country we live in... but at least the internet gives us access to all sorts of tech

@Michelle Davis15
-it's free
-best exchange rates and basically the only way to get certain currencies easily
-fee-free withdrawals up to $250 (for instance, if someone comes from Mexico with Pesos into an account with $150, a major bank like Chase might charge them $30 in fees, whereas Revolut keeps the loss to maybe $10-$20)
-live tracking and the ability to auto-buy any supported currency
-virtual card option for online shopping... you can just delete it afterward so you don't have to worry about whether a site is legit
-setting card limits... you set a max spend of $10 and don't have to stress about someone overcharging you
-ability to freeze the card if it gets lost
-geolocation security features
-free PIN changes

But sure... go ahead and ignore all those advantages

It’s all just cosmetic fluff. There is nothing revolutionary or fundamentally better here. Lowering fees isn't a revolution; a major bank like Chase will do that eventually if they're forced to. And freezing your card? Please, how is that groundbreaking? 🙂

Also, the idea of getting a "better" exchange rate is just misinformation. The interbank mid-market rate is the same for everyone on the planet. The only difference is that Chime offers a better deal because they take a smaller cut, whereas a big bank won't offer it because they don't have to yet. It's not a revolution; it's just slightly cheaper. Once they actually face real competition, those big banks will roll out the exact same features within a month.

On the flip side, a massive bank can afford to be cheap because they have huge volume. Chime can't really compete there because their transaction volume is tiny by comparison. They have to make a living too, and that comes from those fees.

Look, even though I’m a fan of the whole digital banking concept, this gets zero points from me. If they offered just two things—instant payments to any account worldwide and ATM withdrawals at any Mastercard or Visa machine—I’d jump into that headfirst. But as things stand, it looks like all these fintech startups are going to get absolutely crushed by Facebook with their Libra project once they start offering those services. That’s why people were up in arms against it, and why the fintechs are letting them play; they aren't seen as a threat. You have a Facebook account, you have a digital bank. As simple as that.

What's more, Facebook could completely eliminate transaction fees and just charge a monthly subscription. A billion users times $5 a month equals $60 billion a year. Now that's impressive.
Kevin Lee7 Kevin Lee7 Member
29 messages
joined Sep 2019
#38 ·
Michelle Davis15 said:It’s all just cosmetic fluff. There is nothing revolutionary or fundamentally better here. Lowering fees isn't a revolution; a major bank like Chase will do that eventually if they're forced to. And freezing your card? Please, how is that groundbreaking? 🙂

Also, the idea of getting a "better" exchange rate is just misinformation. The interbank mid-market rate is the same for everyone on the planet. The only difference is that Chime offers a better deal because they take a smaller cut, whereas a big bank won't offer it because they don't have to yet. It's not a revolution; it's just slightly cheaper. Once they actually face real competition, those big banks will roll out the exact same features within a month.

On the flip side, a massive bank can afford to be cheap because they have huge volume. Chime can't really compete there because their transaction volume is tiny by comparison. They have to make a living too, and that comes from those fees.

Look, even though I’m a fan of the whole digital banking concept, this gets zero points from me. If they offered just two things—instant payments to any account worldwide and ATM withdrawals at any Mastercard or Visa machine—I’d jump into that headfirst. But as things stand, it looks like all these fintech startups are going to get absolutely crushed by Facebook with their Libra project once they start offering those services. That’s why people were up in arms against it, and why the fintechs are letting them play; they aren't seen as a threat. You have a Facebook account, you have a digital bank. As simple as that.

What's more, Facebook could completely eliminate transaction fees and just charge a monthly subscription. A billion users times $5 a month equals $60 billion a year. Now that's impressive.

You ask what they offer, and then you defend it by saying banks *could* offer the same thing—but clearly, they don't. A BMW could sell a car for the price of a Ford, but they won't.
Gary Baker Gary Baker Newcomer
1 message
joined Sep 2019
#39 ·
Michelle Davis15 said:It’s all just cosmetic fluff. There is nothing revolutionary or fundamentally better here. Lowering fees isn't a revolution; a major bank like Chase will do that eventually if they're forced to. And freezing your card? Please, how is that groundbreaking? 🙂

Also, the idea of getting a "better" exchange rate is just misinformation. The interbank mid-market rate is the same for everyone on the planet. The only difference is that Chime offers a better deal because they take a smaller cut, whereas a big bank won't offer it because they don't have to yet. It's not a revolution; it's just slightly cheaper. Once they actually face real competition, those big banks will roll out the exact same features within a month.

On the flip side, a massive bank can afford to be cheap because they have huge volume. Chime can't really compete there because their transaction volume is tiny by comparison. They have to make a living too, and that comes from those fees.

Look, even though I’m a fan of the whole digital banking concept, this gets zero points from me. If they offered just two things—instant payments to any account worldwide and ATM withdrawals at any Mastercard or Visa machine—I’d jump into that headfirst. But as things stand, it looks like all these fintech startups are going to get absolutely crushed by Facebook with their Libra project once they start offering those services. That’s why people were up in arms against it, and why the fintechs are letting them play; they aren't seen as a threat. You have a Facebook account, you have a digital bank. As simple as that.

What's more, Facebook could completely eliminate transaction fees and just charge a monthly subscription. A billion users times $5 a month equals $60 billion a year. Now that's impressive.


Man, some of the nonsense written here. Like, everything is just wrong—from the interbank rate talk to the idea that banks only refuse to offer these things because they feel like it. Sure, maybe some can offer something similar for retail customers, but what about the business side?! Imagine if those CEOs saw the conversion rates they get as individuals versus the rates their companies get with 1000x more turnover. Plus, these “digital” banks don't come close to the revenue of traditional ones since they don't do loans, guarantees, overdrafts, letters of credit, etc. But then again, they don't have huge overhead either since they don't need a massive staff or physical branches, vaults, and whatever else...

Libra isn't regulated for any other reason than the fact that the US government is scared it might threaten the dollar. Just remember how it ended for everyone else who tried that.

Sen fra my iPhone using Tapatalk
Kevin Morris12 Kevin Morris12 Active MemberOP
230 messages
joined Mar 2020
#40 ·
Has anyone else noticed their debit card offer suddenly vanishing from the app? Is it just me, or is everyone else seeing this too?

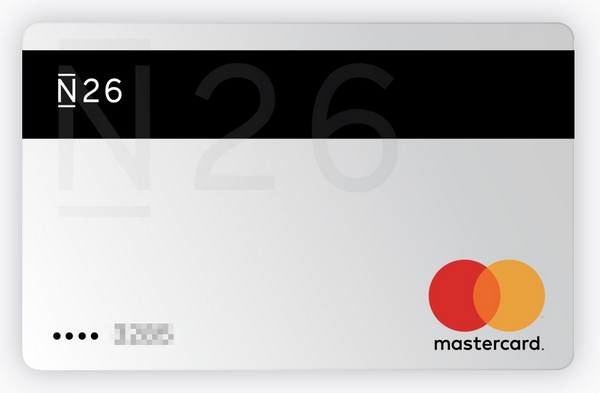
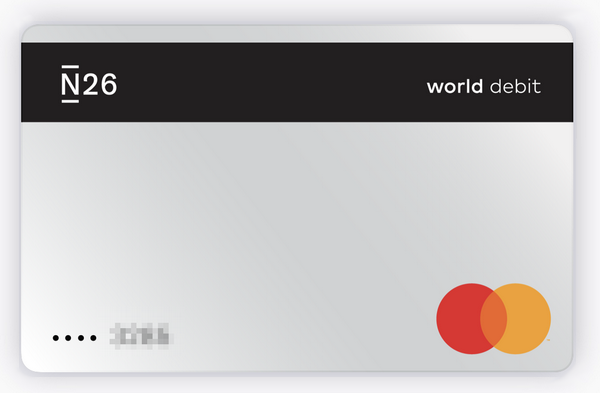
I was frantically swiping right, trying desperately to get my card to show up, when I accidentally tapped the "lock card" button. Of course, that meant I had to re-add everything to Apple Pay. And wouldn't you know it—when I opened my Wallet, the card design had completely changed!🤔

The old look:
image

The new look:
image

Honestly, isn't the old one much better?🕺

You must log in or register to reply here.

Log in Register

🔗 Similar threads