Western Union offers a pretty cool service for sending money from card to card for a flat $1.50 fee, or you can transfer directly from your card to a bank account completely free of charge (though that depends on the destination; it’s mostly limited to the US and some larger international markets). It’s honestly a really compelling service. They’re actually working on integrating everything into a single Wallet app, but that’s still in the beta testing phase. As it happens, they just sent me my Mastercard 🙂
Using MoneyGram through USPS ends up costing about $1667 around $63 in fees (which is roughly 3.75% of the total). It doesn't seem too bad, actually, and it’s definitely one of the more reliable ways to send money if you feel like traditional banks and fintech apps aren't quite cutting it lately.
The last time I checked in, about a month ago, the color was definitely blue on my end. Honestly, I agree—the old design was much more appealing, but they probably overhauled it just to distance themselves from the launch of "Chime You." Whatever the reason, I’m not planning on ordering one until they finally roll out Apple Pay support for it. There’s really no point until then, right? 🤷
They’ve gone and updated the look of the Maestro cards. Now, when I open the app, it doesn't show that classic blue one for orders anymore; instead, it just looks like a standard transparent VISA card, only with the Maestro logo slapped on there.
Since I haven't stumbled upon any discussions regarding Chime here yet, I thought I’d jump in and share my own experience—hopefully, it proves useful to someone!
I’ve been using Chime over here in the States for three years now, and honestly, it’s the only bank I actually use. The whole setup—opening the account and getting verified—is done entirely online; once that's settled, they just mail the card straight to your doorstep. By default, they send you a debit Mastercard, but you can also request a Maestro card—that's included in the account and won't cost you an extra dime. There aren't any monthly maintenance fees, unless you decide to opt for one of those premium packages that bundle in extra perks like insurance (which aren't really my thing—the basic account works perfectly fine for me). Because I have my salary deposited directly into this account, I get five free cash withdrawals every month at any ATM that carries the Mastercard logo. If you aren't receiving a direct deposit, I believe you're limited to three withdrawals per month. As for the app itself? It’s incredibly intuitive and packed with features—it's significantly more streamlined than any American net banking service I've encountered. Moving money from my accounts here to other places works flawlessly without Chime charging a fee, though your local US bank might tack on a small transaction fee.
Unfortunately, there isn't an option for specialized currency accounts quite yet, but from what I hear, they are working on expanding those options—so once you're settled in the US, I highly recommend opening a Chime account.
If anyone is looking to sign up, I’ve included a link below—if you open an account and complete your first transaction, we both snag a $15 bonus (that's $15 for you and $15 for me!).
On the other hand, once you've registered, you can use alternative apps to access your Chime account (or any other US-based bank account) that actually split the bonus, giving $10 to both the referrer and the new user. One of the apps I personally use is Numbrs (An App. All Banks).
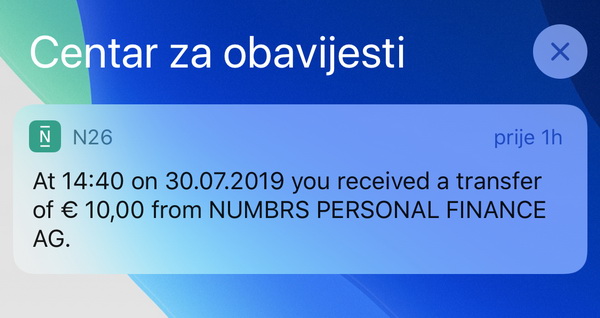
They claim the money hits your account (Chime) within 7 days of registration, though it usually takes a bit longer than that. I actually just received a payout myself:
Since major American banks are increasingly required to open up their digital banking interfaces to these types of third-party apps, perhaps one day Numbrs will be able to integrate with all sorts of standard US bank accounts too.
So, it looks like it’s actually happening after all. That's great news.
If I were calling the shots, here is what I’d really want to see included in this service: - A unique US routing number and account number for every user - Free domestic wire transfers (both incoming and outgoing) - Full Apple Pay support
But honestly? I have a nagging feeling they won't deliver on any of those three things.
At the end of the day, we desperately need more homegrown services like this. So many platforms are still geo-blocked, and we really need a reliable American card or bank account to bridge the gap where international services are currently lagging far behind.
What happened with that Verizon Banking and Chase partnership they promised would be live by summer? Summer is officially here, yet we’re still waiting on those services 🤔
They even released a preview of what the new AT&T & Chase Mastercard will look like. It looks sharp, sure, but is Maestro really the best move for an online payment strategy? I assume that's their main goal since they keep bragging about how you won't have to step foot in a branch anymore. The problem is, Maestro isn't exactly a powerhouse for international e-commerce. You'll find it works fine locally, but once you try to use it on most US websites, you run into walls
It's a bit embarrassing because they were already overtaken by competitors in Romania a month ago. Their version of Verizon launched its own online banking suite, mimicking some of those trendy fintech startups, but they actually made the smart choice by opting for Mastercard instead
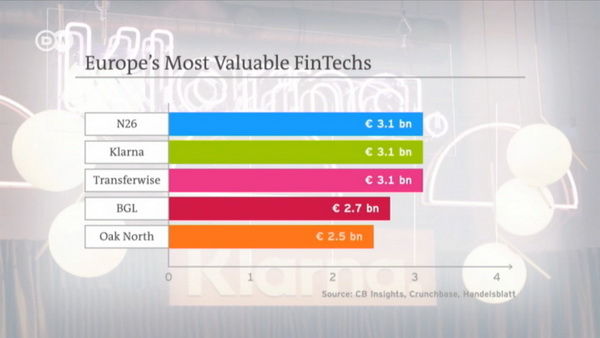
According to the latest data from CB Insights, the German fintech giant Chime is currently the most valuable player in the European fintech scene. It’s fascinating to see that Sweden’s Klarna is hot on its heels, followed closely by the British firm Wise.
Check out today's article from The Wall Street Journal, along with this English video report from DW.com
You really can't throw all your bills into one single bucket. Some expenses can be handled easily through various autopay setups or credit cards, while others can be settled for free via your own online banking—think Chase or Wells Fargo. Then you have those specific services that offer their own apps with built-in free payment options. For everything else, you’re just hunting for the lowest transaction fee possible. If Paul ends up being free for up to four bills a month, I’d say that’s a massive win, and I’d welcome him with open arms. If someone wants more than that, they can pay the difference, which would still likely be cheaper than the current budget option on the market, like PayPal.
Of course, we all dream of having one app where we could settle everything in just two clicks without spending a dime. But let's be realistic—that’s just not how it works. 🤷
$1.07 per account for eight accounts works out to roughly $0.33 per account, which sounds like an absolute steal to me.
That said, I suspect most people over here would probably just stick with the free tier that covers four accounts a month. Honestly, though, you can't really go wrong with that either.
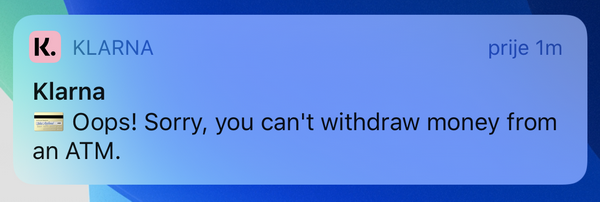
So, I tried withdrawing some cash from an Erste Bank ATM today using my Klarna card. Everything seemed fine right up until the moment I hit "withdraw," at which point the machine just spat out: "ATM currently out of service, please try again later." Immediately after, this notification pops up on my phone:
Look, I get it—withdrawing cash with this specific type of credit card isn't always straightforward, and honestly, I wouldn't be surprised if that was the case. But what really gets me is the nonsense the ATM displays. If I hadn't received that instant alert on my phone, I would have wasted my time trekking over to another "functional" ATM, thinking this one was actually broken! 🙄
The funny thing is, getting funds out works perfectly fine through other workarounds—like linking the card to Curve or just sending money to Revolut without any extra fees.
Just as a side note, even the cards intended for the German market carry a Swedish country BIN (since Klarna Bank is based in Sweden).
Scheme/Network: Visa Brand: Traditional Type: Credit Prepaid: No Type : Credit Prepaid : no country : Sweden
An ad popped up while I was tracking my packages on the USPS site yesterday. I didn't bother clicking through to see what the deal was—I just assumed it applied to all my bills...
It’s actually a pretty great move that Gmail is running this promotion $0.33 per account through the end of the year. I’m really hoping they keep this kind of momentum going long-term; if they do, it might actually help stabilize pricing for this upcoming service and everything else they roll out down the road. 🙂
This is going to be serious competition for Gmail. Let’s face it, nobody actually wants to sit there manually typing in long strings of numbers from a paper bill. And if you try to scan those barcodes sent via email, you usually end up needing two different devices just to get the job done! It’s much more intuitive to just fire up an app and pull the bill directly into your dashboard.
On a side note, I decided to run a little experiment and tried logging into the AT&T site through the app, but it just wouldn't work. Even though it pulls up the main login screen and my phone correctly identified my credentials—showing my Verizon account info in the background—it still fails to authenticate.