Here’s a simple workaround: open a German PayPal account and link it to that US Dollar account you set up through Wise using your German IBAN. Once that's linked, just transfer the funds from your American PayPal to your German one, then pull the money straight into your Wise account. It's that easy! Just keep in mind it usually takes about two or three days for the funds to actually show up in your Wise account.
It seems like everyone has suddenly rushed toward the US lately, hasn't it? I have to say, seeing this surge for Chime specifically makes me really happy. Out of all the fintech services out there, they’ve managed to become one of the biggest players—if not quite the largest. 👍
Chime is honestly a fantastic service. I’ve been using it for my Apple Pay transactions, and so far, everything has been seamless. It would be great if they offered USD support when I head back to the States, though I realize that might be a stretch since they don't even carry the local currency in much larger markets yet. But hey, you never know, right? 🍿
It looks like N26 has already reached out to the Federal Reserve—they're clearly making their move to enter the American market.
Once a bank from another EU member state sends over a passport notification, they can step right in and start offering services here in America immediately. Isn't that efficient?
It looks like Revolut isn't the only player eyeing an expansion into the American market. According to reports from the Wall Street Journal, its biggest rival—the Berlin-based N26, which stands as one of the most valuable mobile banks in Europe—has already gone a step further by making several strategic moves to prepare for its entry into the US. Is the competition about to heat up even more?
With the buzz surrounding Revolut’s announcement—one of the two biggest mobile banking giants in Europe—about entering the American retail market this summer to go toe-to-toe with our top ten major banks, there is another player making quiet moves. N26 has already "notified" the Federal Reserve, effectively checking off all the boxes needed to start offering services here. While N26 is already up and running in Canada, they haven't shared any specific details regarding further expansion plans just yet. Could we be seeing more competition on the horizon?
When we reached out to the Federal Reserve regarding mobile banking apps and other fintech players planning to enter the American market, they pointed us toward the list found under the "passport notification." It’s quite an extensive roster, featuring over 170 banks from all corners of the globe that are authorized to offer services here thanks to the European banking passport. Looking through the names, you see some of the absolute heavyweights of the global financial world. We're talking about major American institutions like Wells Fargo, Morgan Stanley, and JPMorgan Chase, alongside international giants such as the UK's HSBC, the Netherlands' ING, Germany's Deutsche Bank, and France's BNP Paribas. The list even stretches across the Pacific to include Japan's Mizuho and China's Bank of China. Interestingly, even Rakuten Bank—linked to one of Japan's largest internet conglomerates—is included on there. Isn't it fascinating to see just how much global competition is poised to step onto our shores?
Most of the banks listed here are primarily focused on massive institutional investments and government projects rather than true retail banking. When we talk about retail banking, we’re really talking about everything from basic checking accounts to consumer loans—and if you broaden the scope to commercial banking, that includes services for small business owners too. Interestingly, though, looking through that Federal Reserve list, we actually found Chime, the mobile banking platform based out of Berlin.
A financial institution from another European Union member state can start providing services directly here in the States as soon as the Federal Reserve receives a passport notification detailing exactly which services they intend to offer. The Federal Reserve publishes these notifications publicly, meaning the institution doesn't need to go through any additional permit processes. Isn't that a streamlined way to handle things?
Chime, which boasts a market valuation of $2.7 billion and has secured backing from heavyweights like Allianz and Tencent, has already signaled its intentions to the Federal Reserve. According to recent filings, they are looking to establish a foothold in the American market by offering checking accounts and accepting deposits. On top of that, they're eyeing the lending space—including consumer loans—alongside various other payment services. Isn't it interesting to see how quickly these fintech players move to shake up the traditional banking landscape?
According to the Federal Reserve, there is currently only one player from another European Union member state operating in our domestic market that focuses primarily on digital banking—specifically those services you can sign up for directly online—and that would be the Finnish lender Ferratum. As for the other banks, the Federal Reserve notes they are currently in the process of developing their digital offerings. The central bank also took the time to explain why local financial institutions have been paying such close attention to the news of Revolut’s arrival, especially since Revolut announced plans to integrate USD into its app. It really comes down to this: citizens already have the right to open an account in any bank within the European Union and receive their salary there. With new players like Revolut and Chime entering the fray, wouldn't you agree that making that entire process completely seamless is the logical next step?
"The ability to freely open transaction accounts abroad without needing prior approval from the Federal Reserve—which used to be required only if the account was opened for specific designated purposes—was actually implemented back in January 2011. The Federal Reserve maintains that an employer resident here can pay a resident employee exclusively in USD, provided the payment is being made into an account held at a foreign-based bank," according to statements from the Federal Reserve. The Federal Reserve further clarifies that while special permits aren't necessary, all foreign players operating within the US must still abide by American laws. They noted that these institutions must comply with the Law on Credit Institutions, specifically regarding consumer protection (Articles 300-312), along with all other relevant regulations.
"Even though supervision of such institutions falls under the regulator of their home country, if the Federal Reserve spots any illegal activity, we notify the appropriate authority in that EU member state's home country. We can also request mediation through the European Banking Authority and have the power to mandate preventive measures," the Federal Reserve concluded.
Sure, I’m aware there are limits, but since we're talking about a free account, it’s more than enough for what most people need. Plus, you can use that card pretty much anywhere just like any standard American debit card, so you won't really be hunting for cash. But if you do find yourself needing some, the amount they provide without any extra fees is perfectly reasonable.
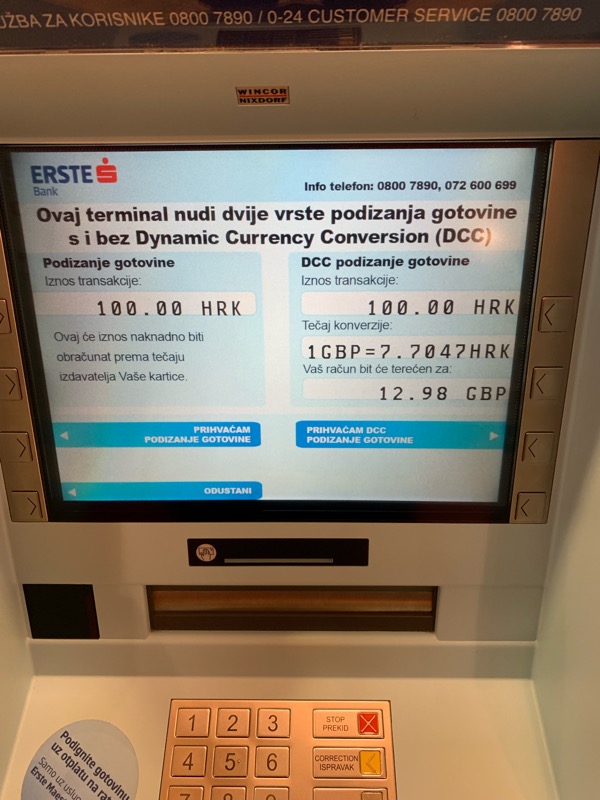
I’ve always relied on Wise to move money from my PayPal account, and honestly, they’ve been fantastic. But yesterday, after receiving my free Mastercard—which is a really sleek green design featuring the "Hello World" 😍 logo—I decided to take it out for a spin and see how it handles actual shopping. My first trip to Walmart this morning went perfectly fine, though I was a bit puzzled by the POS terminal. Before I even entered my PIN, it was offering me a choice between USD and British Pounds. It felt a little strange since my account is strictly in Dollars, and I have zero connection to pounds, other than the fact that the issuing bank is British and the card's registered location shows the United Kingdom. I assume that's why it's happening?
I also headed out to try an ATM withdrawal. The transaction went through $33 without any extra fees at either a JPMorgan Chase or a JP Morgan ATM, but again, the machine kept pushing me to withdraw in USD or convert directly $33 into British Pounds. Since I don't hold any pounds in my account, I have no idea where the funds would even come from if I had selected that option 🤔. Is there actually a way to just withdraw from my Dollar account, or am I stuck with these USD and Pound prompts?
All things considered, this is such a great setup, especially for withdrawing cash using a credit card. You can essentially pull $33 from your credit card for just the standard $0.13 Wise fee and then withdraw it for free using the Wise card at any ATM here in the States. Most ATMs seem to be totally free to use—I think only Euronet machines charge a small fee, but let's be honest, nobody uses those anyway—plus you avoid those massive cash advance fees from the credit card companies. Both the Wise account and the card itself are completely free.
I’m looking at picking up a computer through Craigslist, and the seller is planning to ship it to me—I'll be paying upon delivery. Since I won't be there in person to test the machine the moment the package arrives, I'm wondering: is there any kind of window where I can freeze the payment if the device turns out to be defective? It isn't a particularly expensive setup, so it doesn't really make sense to go through an expensive service like Amazon just to get their two-day payment protection window.
I’ve been digging through the Venmo FAQ, and it mentions you can use it at various supported retailers—specifically those that also accept Apple Wallet. Does anyone actually know which locations support Venmo? I can't seem to find a specific list anywhere. It used to be that Apple Wallet had a directory right in the app, though back then the selection was pretty slim—maybe around 20 spots, mostly just small coffee shops or local barbershops around Washington, D.C. Now, I’m looking through everything and I can't find a single merchant listed. 🤔
Of course, they definitely need those services, but if you look at the data, peer-to-peer transfers are also seeing a massive surge. It’s not an "either-or" situation; one doesn't rule out the other.
Hmm, but aren't you ignoring the obvious facts here? We see digital transfers through various online services growing exponentially every single day. People are moving their lives online, which naturally creates an massive demand for digital payment options. Can you point to even one single fact that contradicts that trend?
Besides, there’s a million different ways to solve any given problem, and sending money is no exception. Using ExxonMobil or Cash App is just one way to handle it. In certain situations, they’re actually faster and much more convenient than traditional methods.
I’m a bit confused—are you actually speaking on behalf of everyone when you claim people won't need these? We are talking about mobile payment apps here; discussing which type of service fits which user is a perfectly normal conversation. In fact, if you look closely, about 80% of what I mentioned above is explicitly stated in the app descriptions themselves regarding their target audience.
It seems we’re looking at two different worlds here. I’m actually in need of services like these, whereas you clearly aren't—so where does that leave us? At the end of the day, everything boils down to the individual. It all comes down to whether there's a demand, and frankly, isn't it obvious that demand is growing every single day?
Charles Ramos7 said:If they have someone willing to give them money, why wouldn't they just hand over cash? 🤔 If kids can't handle technology, surely their parents or grandparents can. 🤣 At the end of the day, receiving money isn't the hard part; it's navigating the tech that's the hurdle.
It’s the exact same reason people lean on services like Venmo or PayPal—it's all about that sense of security. Why deal with the stress when you can ensure the sender isn't just two steps away from your account?
Charles Ramos7 said:If they have someone willing to give them money, why wouldn't they just hand over cash? 🤔 If kids can't handle technology, surely their parents or grandparents can. 🤣 At the end of the day, receiving money isn't the hard part; it's navigating the tech that's the hurdle.
Teenagers seem to have their lives figured out, yet they rarely have their own bank accounts. Meanwhile, older folks usually face the exact opposite problem. It makes you wonder—is anyone actually built for using Venmo?
ironcyclist58 said:Look, you could also put it this way: Venmo is way more versatile and fits right into your daily routine. It covers most of what you'd actually need, which basically pushes Venmo into a niche corner where it’s only used for really specific, niche stuff rather than everyday life.
But honestly, it doesn't really offer anything that Venmo isn't already doing—unless we decide to lump all money transfers into one single category. If we do that, we could just say we have PayPal and a billion other similar services that move money from one account to another, making this new service totally redundant. Oh, and there are no fees yet; that’s the one bright spot I can see, though it'll probably disappear once the service really takes off. But hey, let's just agree to disagree, shall we? 😛
If you ask me, speed isn't even the main issue here. Venmo just operates on a completely different wavelength and targets a totally different demographic.
While PayPal is your standard account-to-account transfer tool—something you simply can't do with Venmo—the mechanics are fundamentally different. With Venmo, withdrawing cash means heading in person to an ExxonMobil station, and when sending money, you have the choice between using a card or ExxonMobil funds. Right there, the two services are worlds apart. This naturally attracts a different crowd—people who might not have a traditional bank account, teenagers, those with frozen credit, or anyone who isn't particularly tech-savvy or comfortable managing bank cards and accounts. These are the people for whom PayPal offers zero utility, at least in those specific scenarios. And let’s not forget the perks I mentioned earlier: imagine forgetting your wallet at home and being able to pull cash from an ExxonMobil station right from your phone, or withdrawing via credit card for a small fee. Sure, using Venmo for things like betting shops or prepaid vouchers feels a bit pointless to me, but hey, the option is there. Ultimately, I don't think speed is the deciding factor because there are countless situations where PayPal just won't work for you, whereas Venmo can step in and solve the problem (and vice versa). Honestly, it's a great thing that these two services are so distinct; we really don't need ten different apps all trying to do the exact same thing.
ironcyclist58 said:If you send it during business hours, even Kellogg's can be pretty quick—maybe within an hour. But if you try it late in the afternoon or over the weekend, don't expect anything until the next business day morning...
Kellogg's handles that too.
Is that actually fee-free, or are they hitting you with standard fees? If it's free, then fine. If there's a cut, it's basically useless...
The assumption is you already have a checking or savings account at some local bank here in the States. That should be plenty...
I haven't personally bought any gift cards, but when you use them at places like DraftKings or the lottery, you're looking at about a 4% fee—though I wouldn't say that makes them useless. We shouldn't be comparing PayPal to Venmo and trying to crown one as "better" than the other, right? They serve completely different purposes in the world of money transfers, and honestly, it's a good thing we have such diverse options available to us.
Does anyone happen to know of an app that works with Western Union for receiving funds? I’m talking about small monthly payments—around $110 or so—coming from Google US. Right now, I have to go down to the local Post Office to pick up the cash without any fees, but is there an actual money transfer app that would let me move those funds directly into my bank account instead? 🤔
It’s honestly such a breath of fresh air that they haven't just restricted everything to domestic transactions, unlike some of those other international services we see out there.
They both have their merits depending on the situation. Nabisco is great for those "low-stakes" moments when you aren't in a rush and the other person has an account you can just transfer funds to. On the flip side, Cash App is your go-to for lightning-fast transfers—especially if the person you're paying doesn't have a traditional bank account, if you accidentally left your wallet at home, or if you're dealing with someone whose accounts are temporarily frozen. It’s also a solid choice if you want to withdraw cash using a credit card while keeping those pesky transaction fees to a minimum.
I'm actually curious, does Nabisco support international cards? I tried using a foreign virtual Mastercard on Cash App yesterday, and it went through without a single hitch.
What exactly counts as two different products here?
ExxonMobil is a great choice since they’re usually open 24/7, though it would be pretty handy if places like the Associated Press offered similar access.
I came across an article from November 2018 that’s actually quite relevant here; it looks like a new competitor for PayPal, an app called "Stripe," is hitting the market in early 2019.
On a different note, I have to give a shout-out to the Aircash app. It’s honestly a lifesaver if you accidentally leave your wallet at home and find yourself needing cash. You just pull the funds via your card, head to the nearest ExxonMobil station with the code, and boom—you've got your cash right there for a tiny fee. Since the app supports credit cards too, and their withdrawal fee for, say, $67 is only $1.75, it actually turns out to be cheaper than hitting an ATM with certain credit cards where those fees can really bite you.
ironcyclist58 said:It says so right there in the terms, and honestly, I’ve actually tried it myself—not exactly recently, though, more like a few years back. Where exactly is it showing you that it's possible?
When I try to set up a new transfer, the "purpose of payment" options are honestly hilarious—they all basically imply you're just sending money privately to someone.
But you're right, it actually won't work. I just tried it myself: once you type in your own Routing Number at the end and hit save, it throws an error saying "payment to the entered Routing Number is not permitted." What a bummer.