CheckEmoji Community · the emoji forum
🏠 Home 🆕 What's new ❓ Unanswered 🔥 Popular 📡 RSS Members 👥 0 online log in · register
Home › Society › Economy › Banking, Insurance & Loans › Best mobile apps for money transfers?

Best mobile apps for money transfers?

Started by lonedriver18 · · 👁 16 views · 539 replies

📡 Subscribe to replies

Participants lonedriver18Charles Ramos7ironcyclist58Chris Mitchell11Zachary Ward5George Lewis9Arthur Green5Henry Robinson3rapidskipper12electricbadger89Taylor Gray5slystag3Kevin Morris12darkmaker94David Garcia21cosmichawk67brighttinker48rowdyhawk14James Rogers53analoghound19nimblefox14Jose Miller3briskcanyon12driftingtinker77 …
ironcyclist58 ironcyclist58 Regular
863 messages
joined Feb 2020
#121 ·
Kevin Morris12 said:Business Insider just put out a piece about this new bill-pay app launching this fall. Technically, the app is already live, but it’s pretty much non-functional right now. That said, if they actually deliver on the promise of letting you pull up and pay all your bills directly within the interface, wouldn't that be a total game-changer?

It looks like that Romanian Pag is in quite a rush to win over American users, since they're already pushing people to download the alpha version.

Personally, I couldn't care less about that. I just want to scan a barcode and be done with it.
Kevin Morris12 Kevin Morris12 Active Member
230 messages
joined Mar 2020
#122 ·
To all me, this seems incredibly redundant. What’s the point of scanning a bill's barcode if you're just going to receive that same bill in your inbox and pay it in three clicks anyway? And we're talking about handling ten different bills at once. That's the concept, at least—though whether they can actually pull off such a seamless execution remains to be seen.

Actually, this specific section of the article is far more intriguing to me than the app itself:

For startups looking to break into the market here, this represents a massive opportunity—especially since banks will be required to open up their IT interfaces by mid-September due to the PSD2 directive, allowing users to pay bills directly through various third-party apps.


I wasn't aware that banks would be mandated to grant access via third-party applications starting this September. This is a fantastic development! I've seen how smoothly this works with banks in Germany; you can elegantly access your online banking through a variety of apps that have nothing to do with your primary bank. By using your existing bank credentials, you log directly into these third-party platforms, which lets you consolidate accounts from four or five different banks into one interface. Beyond that, these apps can offer features your traditional online banking might lack—you could even apply for various credit cards in practically three clicks (by giving the credit providers a view of your account status). If I recall correctly, isn't this also a prerequisite for linking a bank account to PayPal for direct debits? It opens the door to all sorts of instant payment services tied directly to your account; in Germany, for instance, they use Venmo, or in the Netherlands, they use ideal and things like that. In Germany, these systems are even used for identity verification when accessing services that require personal data; instead of jumping through all those hoops, you simply allow them to verify you through your online banking. Here in the States, we have something similar starting to take shape through services like Login.gov.
ironcyclist58 ironcyclist58 Regular
863 messages
joined Feb 2020
#123 ·
Kevin Morris12 said:To all me, this seems incredibly redundant. What’s the point of scanning a bill's barcode if you're just going to receive that same bill in your inbox and pay it in three clicks anyway? And we're talking about handling ten different bills at once. That's the concept, at least—though whether they can actually pull off such a seamless execution remains to be seen.

Actually, this specific section of the article is far more intriguing to me than the app itself:

For startups looking to break into the market here, this represents a massive opportunity—especially since banks will be required to open up their IT interfaces by mid-September due to the PSD2 directive, allowing users to pay bills directly through various third-party apps.


I wasn't aware that banks would be mandated to grant access via third-party applications starting this September. This is a fantastic development! I've seen how smoothly this works with banks in Germany; you can elegantly access your online banking through a variety of apps that have nothing to do with your primary bank. By using your existing bank credentials, you log directly into these third-party platforms, which lets you consolidate accounts from four or five different banks into one interface. Beyond that, these apps can offer features your traditional online banking might lack—you could even apply for various credit cards in practically three clicks (by giving the credit providers a view of your account status). If I recall correctly, isn't this also a prerequisite for linking a bank account to PayPal for direct debits? It opens the door to all sorts of instant payment services tied directly to your account; in Germany, for instance, they use Venmo, or in the Netherlands, they use ideal and things like that. In Germany, these systems are even used for identity verification when accessing services that require personal data; instead of jumping through all those hoops, you simply allow them to verify you through your online banking. Here in the States, we have something similar starting to take shape through services like Login.gov.

It’s because you’re basically being locked into their ecosystem. What happens when you want to pay a bill with cash one month, or use a different method entirely? Or what if the app crashes right when you actually need to pay something? With a standard barcode payment, you can handle any random bill, even if the app doesn't have a direct partnership with the provider...
Kevin Morris12 Kevin Morris12 Active Member
230 messages
joined Mar 2020
#124 ·
I wouldn't go so far as to say you're "stuck." You only really find yourself trapped if you let things get to a point where that's your only way to settle a bill. In any modern market, there will always be X other ways to get things done. It’s a bit like saying you're tied to your specific Chase online banking app and then blaming them because you missed a payment one month. At the end of the day, they’re just one option among many. Even with barcode scanning, there’s always a third-party service running in the background that could potentially go offline right when you need it most. 🙂
ironcyclist58 ironcyclist58 Regular
863 messages
joined Feb 2020
#125 ·
The real headache here is switching everything over to the app (I'm assuming if you opt for digital, they stop sending paper statements or anything else through the mail). My main concern is what kind of "format" these bills actually come in once you go digital... like, will you still have all the essential info—account numbers, payment references, and whatnot—to pay it through another method? It reminds me of setting up auto-pay with a big bank like Chase; sometimes you lose that flexibility to just manually pay the bill via a different way if things change...
Kevin Morris12 Kevin Morris12 Active Member
230 messages
joined Mar 2020
#126 ·
You’ll still have plenty of ways to settle those bills. There's a big difference between a provider simply "handling the heavy lifting" by processing the payment and just sending you a usage alert without a bill, versus a system where you still need to step in to authorize or complete the transaction. That’s typically how these types of services are structured. Even today, when you opt for e-billing with most major companies, you often receive a standard invoice via email, but you can then zap the payment in just two or three clicks through their official app. This should work much the same way—except instead of jumping between a dozen different apps, you'll be able to manage everything from one central hub.

But hey, let's just sit tight and see how they actually roll this out once it arrives.
ironcyclist58 ironcyclist58 Regular
863 messages
joined Feb 2020
#127 ·
Sure, but the real win with barcodes is that you can pay off pretty much any bill you want.
That would basically put them right up against Gmail as competition.
Kevin Morris12 Kevin Morris12 Active Member
230 messages
joined Mar 2020
#128 ·
This is going to be serious competition for Gmail. Let’s face it, nobody actually wants to sit there manually typing in long strings of numbers from a paper bill. And if you try to scan those barcodes sent via email, you usually end up needing two different devices just to get the job done! It’s much more intuitive to just fire up an app and pull the bill directly into your dashboard.

On a side note, I decided to run a little experiment and tried logging into the AT&T site through the app, but it just wouldn't work. Even though it pulls up the main login screen and my phone correctly identified my credentials—showing my Verizon account info in the background—it still fails to authenticate.
ironcyclist58 ironcyclist58 Regular
863 messages
joined Feb 2020
#129 ·
It’ll probably support both, honestly. I was just saying the barcode option caught my eye... mostly because I'm hoping it fixes those annoying gaps with Gmail, like the high fees and the fact that you can't even send money to certain accounts.
Kevin Morris12 Kevin Morris12 Active Member
230 messages
joined Mar 2020
#130 ·
It’s actually a pretty great move that Gmail is running this promotion $0.33 per account through the end of the year. I’m really hoping they keep this kind of momentum going long-term; if they do, it might actually help stabilize pricing for this upcoming service and everything else they roll out down the road. 🙂
ironcyclist58 ironcyclist58 Regular
863 messages
joined Feb 2020
#131 ·
Isn't this just some campaign for those e-invoices (the ones they're forcing everyone to send to government contractors starting July 1st)?
Kevin Morris12 Kevin Morris12 Active Member
230 messages
joined Mar 2020
#132 ·
Yeah, I see that now. That’s a real shame. 👎

An ad popped up while I was tracking my packages on the USPS site yesterday. I didn't bother clicking through to see what the deal was—I just assumed it applied to all my bills...
ironcyclist58 ironcyclist58 Regular
863 messages
joined Feb 2020
#133 ·
I’m looking over this slightly older article about Paul’s arrival, and honestly, if they implement a pricing structure here similar to what they have in Romania, they might as well just shut the whole thing down right now...
Kevin Morris12 Kevin Morris12 Active Member
230 messages
joined Mar 2020
#134 ·
$1.07 per account for eight accounts works out to roughly $0.33 per account, which sounds like an absolute steal to me.

That said, I suspect most people over here would probably just stick with the free tier that covers four accounts a month. Honestly, though, you can't really go wrong with that either.
ironcyclist58 ironcyclist58 Regular
863 messages
joined Feb 2020
#135 ·
If you ask me, these apps only really matter if they actually replace everything else—like, if they become the one-stop shop for every single bill you have. Just being able to handle four different bills isn't even close to enough. You’d still be stuck juggling all your old payment methods plus adding yet another app to the mix, which just feels pointless. The whole point of this tech is supposed to simplify our lives by cutting down on the number of apps we need, not making things more cluttered...
Kevin Morris12 Kevin Morris12 Active Member
230 messages
joined Mar 2020
#136 ·
You really can't throw all your bills into one single bucket. Some expenses can be handled easily through various autopay setups or credit cards, while others can be settled for free via your own online banking—think Chase or Wells Fargo. Then you have those specific services that offer their own apps with built-in free payment options. For everything else, you’re just hunting for the lowest transaction fee possible. If Paul ends up being free for up to four bills a month, I’d say that’s a massive win, and I’d welcome him with open arms. If someone wants more than that, they can pay the difference, which would still likely be cheaper than the current budget option on the market, like PayPal.

Of course, we all dream of having one app where we could settle everything in just two clicks without spending a dime. But let's be realistic—that’s just not how it works. 🤷
ironcyclist58 ironcyclist58 Regular
863 messages
joined Feb 2020
#137 ·
Kevin Morris12 said:You really can't throw all your bills into one single bucket. Some expenses can be handled easily through various autopay setups or credit cards, while others can be settled for free via your own online banking—think Chase or Wells Fargo. Then you have those specific services that offer their own apps with built-in free payment options. For everything else, you’re just hunting for the lowest transaction fee possible. If Paul ends up being free for up to four bills a month, I’d say that’s a massive win, and I’d welcome him with open arms. If someone wants more than that, they can pay the difference, which would still likely be cheaper than the current budget option on the market, like PayPal.

Of course, we all dream of having one app where we could settle everything in just two clicks without spending a dime. But let's be realistic—that’s just not how it works. 🤷

But honestly, that’s the only way those kinds of apps actually survive. That’s why they have over 70% market share in places like Sweden—because they're free for regular people. Only the businesses taking the payments actually foot the bill.
If they were free for everyone, people would ditch direct debits and all those clunky individual banking apps in a heartbeat. From a money standpoint, there'd be no difference, and having everything in one spot is just easier. Most people aren't going to bother juggling five different apps... maybe us "fintech nerds" would, but the average person? No chance.

Stripe and Oreo are free to use, yet only a tiny handful of people even touch them, let alone want to pay for them.
ironcyclist58 ironcyclist58 Regular
863 messages
joined Feb 2020
#138 ·
I'm looking at the companies available on Martha's Vineyard and honestly, the options aren't great. If you take out the ones that can just pay under the table through other means, all I see is Exelon heating...
Kevin Morris12 Kevin Morris12 Active Member
230 messages
joined Mar 2020
#139 ·
What happened with that Verizon Banking and Chase partnership they promised would be live by summer? Summer is officially here, yet we’re still waiting on those services 🤔

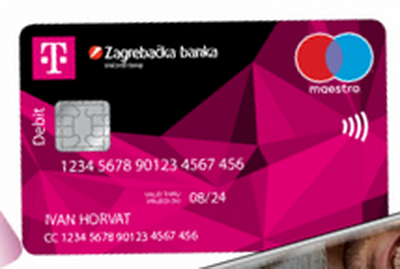
They even released a preview of what the new AT&T & Chase Mastercard will look like. It looks sharp, sure, but is Maestro really the best move for an online payment strategy? I assume that's their main goal since they keep bragging about how you won't have to step foot in a branch anymore. The problem is, Maestro isn't exactly a powerhouse for international e-commerce. You'll find it works fine locally, but once you try to use it on most US websites, you run into walls

image

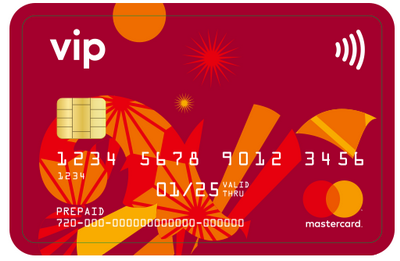
It's a bit embarrassing because they were already overtaken by competitors in Romania a month ago. Their version of Verizon launched its own online banking suite, mimicking some of those trendy fintech startups, but they actually made the smart choice by opting for Mastercard instead

image
ironcyclist58 ironcyclist58 Regular
863 messages
joined Feb 2020
#140 ·
Do you have a link for that Mexican Verizon service?

You must log in or register to reply here.

Log in Register

🔗 Similar threads